Hospitality and mixed-use properties
Separate building repairs, equipment, contents and operating records. Record access restrictions and repair milestones without assuming every lost reservation or expense is covered.
A fire, storm or water loss can interrupt an apartment community, school campus or hospitality property long after emergency cleanup ends. ICRS helps policyholders document the covered damage and present a clear, supported claim.
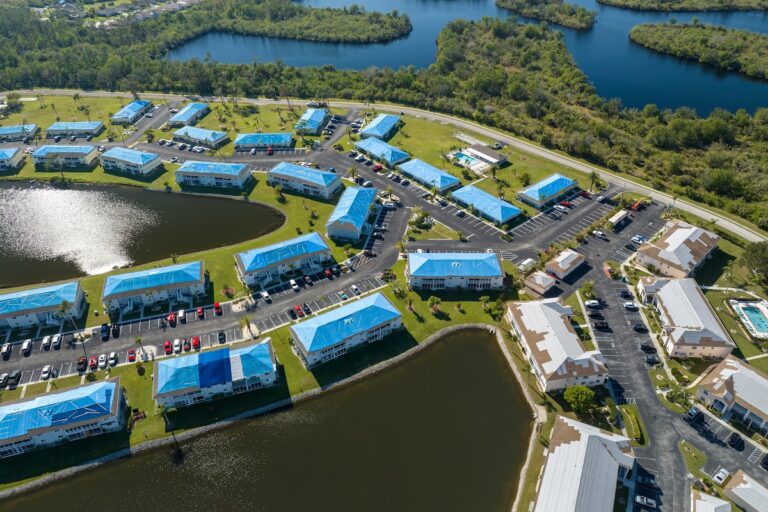
Illustrative stock photograph of storm damage; not a specific ICRS claim or Florida location.
Service area: Orlando, Kissimmee, Sanford, Winter Park, Clermont and surrounding Central Florida communities.
Claims of $250,000+ after deductible: full public-adjusting representation for qualifying property losses.
Claims under $250,000: Claim Navigator provides paid strategic guidance, with the option for full representation when appropriate.
Hotels, commercial buildings, apartments, associations, churches, schools and high-value homes.
ICRS exclusively represents policyholders. We help document the physical loss, evaluate the repair scope and communicate the supported claim to the insurer. Each engagement begins with the insured entity, applicable policy and written representation terms.
Central Florida properties may combine guest or resident areas, commercial kitchens, mechanical rooms, offices and shared amenities. A single summary estimate can conceal important differences between these spaces. Map the affected areas, identify who owns the damaged property and organize estimates by trade. Keep inspection notes and invoices connected to the specific condition each contractor addressed.
Separate building repairs, equipment, contents and operating records. Record access restrictions and repair milestones without assuming every lost reservation or expense is covered.
Include affected classrooms, worship spaces, kitchens, offices and shared equipment in the inspection record. Keep temporary-use costs and repair costs in separate categories.
Document the source, discovery date, affected materials and mitigation work. Preserve evidence of smoke, heat and water impacts before damaged materials are removed, when safe.
Yes. A review can compare the carrier’s estimate and payment explanation with the policyholder’s documented damage and repair information. Representation depends on the policy, facts, timing and written agreement; a prior payment does not establish what additional amounts, if any, are owed.
No. Repair cost alone does not establish coverage or the amount after deductible. The policy, insured property, cause of loss, supporting evidence and deductible all matter. Share the actual records before selecting a service.
Prioritize safety and necessary steps to protect the property. Follow applicable policy duties, keep receipts and document conditions before cleanup or demolition when safe. Do not delay urgent safety work while waiting for a consultation.
Read a published ICRS apartment wind-claim example. This is a separate claim example, not a stated result in Orlando; prior outcomes do not predict another claim.
Florida Insurance Consumer Advocate provides public insurance-claim information. For your property, use the actual policy and carrier correspondence to identify the relevant requirements.
ICRS provides paid public adjusting services. Consultation and contingency representation fees depend on the service and written agreement. Coverage, representation and any recovery depend on the policy and facts of loss.
Request a property claim review
Explore paid Claim Navigator guidance for claims under $250,000
Service-area pages describe where ICRS reviews claims. They do not identify a local office or guarantee inspection timing. Updated October 19, 2026.
FREE ICRS COMMERCIAL CLAIM RESOURCES
Seven practical PDF guides for commercial and multifamily property owners: the full Resource Kit, the First 72 Hours field guide, four companion checklists, and the 52-jurisdiction source index.
Enter your details below for immediate access to the downloads.
Educational resources only. Requesting the guides does not create a public adjuster engagement or guarantee a claim result. We handle your information under our Privacy Policy.
