Condominium common property
Record roof sections, exterior walls, shared equipment, stairways and access systems individually. Obtain maintenance and pre-loss records when available.
A major coastal property loss can involve roofs, building envelopes, elevators, shared utilities and rental operations. ICRS represents policyholders who need a documented repair scope and a coordinated approach to their property insurance claim.
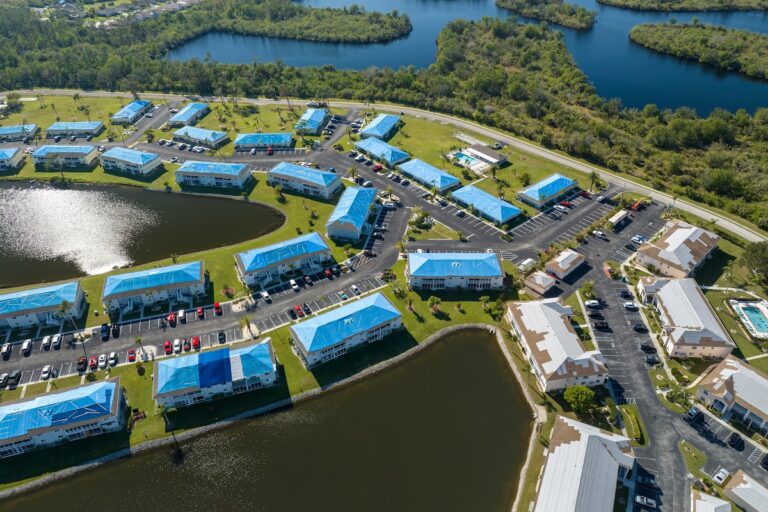
Illustrative stock photograph of storm damage; not a specific ICRS claim or Florida location.
Service area: Destin, Fort Walton Beach, Miramar Beach, the 30A communities, Panama City and Panama City Beach.
Claims of $250,000+ after deductible: full public-adjusting representation for qualifying property losses.
Claims under $250,000: Claim Navigator provides paid strategic guidance, with the option for full representation when appropriate.
Condominium associations, HOAs, apartment communities, hotels, retail properties, churches, schools and high-value coastal homes.
ICRS exclusively represents policyholders. We help document the physical loss, evaluate the repair scope and communicate the supported claim to the insurer. Each engagement begins with the insured entity, applicable policy and written representation terms.
An association’s common-property claim is different from a unit owner’s interior claim or an operator’s business-income claim. For properties along the Emerald Coast, create an inventory that identifies the building, ownership or association responsibility, damaged component and responding policy. This helps the board and property manager keep their own claim evidence organized without assuming every unit or expense belongs under one policy.
Record roof sections, exterior walls, shared equipment, stairways and access systems individually. Obtain maintenance and pre-loss records when available.
Preserve occupancy records, canceled reservations, repair access dates and mitigation costs. Any business-income request must be supported by the policy and financial records.
Separate structural damage, water-entry paths and temporary stabilization. Flood, wind and other causes should be evaluated against the actual policies rather than treated as interchangeable.
A manager can help gather records, but the named insured and authorized board or owner should be identified before representation is agreed. ICRS clarifies the policyholder, decision-maker and claim scope during the initial review.
No. Repair cost alone does not establish coverage or the amount after deductible. The policy, insured property, cause of loss, supporting evidence and deductible all matter. Share the actual records before selecting a service.
Prioritize safety and necessary steps to protect the property. Follow applicable policy duties, keep receipts and document conditions before cleanup or demolition when safe. Do not delay urgent safety work while waiting for a consultation.
Read a published ICRS apartment wind-claim example. This is a separate claim example, not a stated result in Emerald Coast; prior outcomes do not predict another claim.
Florida Insurance Consumer Advocate provides public insurance-claim information. For your property, use the actual policy and carrier correspondence to identify the relevant requirements.
ICRS provides paid public adjusting services. Consultation and contingency representation fees depend on the service and written agreement. Coverage, representation and any recovery depend on the policy and facts of loss.
Request a property claim review
Explore paid Claim Navigator guidance for claims under $250,000
Service-area pages describe where ICRS reviews claims. They do not identify a local office or guarantee inspection timing. Updated October 19, 2026.
FREE ICRS COMMERCIAL CLAIM RESOURCES
Seven practical PDF guides for commercial and multifamily property owners: the full Resource Kit, the First 72 Hours field guide, four companion checklists, and the 52-jurisdiction source index.
Enter your details below for immediate access to the downloads.
Educational resources only. Requesting the guides does not create a public adjuster engagement or guarantee a claim result. We handle your information under our Privacy Policy.
