Commercial and multifamily
Apartment complexes, offices, retail centers and industrial properties with building damage and potential operational disruption.
When a fire or storm damages your building, the insurance claim can become a project of its own. ICRS helps property owners and managers document the loss and pursue a fair settlement.
Commercial buildings. Apartment complexes. Churches. Associations. High-value homes.
Request a Claim ReviewBased in Lakeway, Texas • Serving policyholders in Houston and Katy
Large losses in Houston and Katy may raise separate questions about wind, water intrusion, flooding, equipment and interrupted operations. Our licensed public insurance adjusters help property owners and managers organize the facts and documentation for the applicable property claim.
Keep the timing, location and observed source of damage clear. Different policies, causes of loss and deductibles may need separate review; the appearance of water damage alone does not establish coverage.
Understand what a public adjuster does →Meet ICRS and learn about our work with property insurance claims.
Apartment complexes, offices, retail centers and industrial properties with building damage and potential operational disruption.
Religious organizations, HOA and condominium associations, schools and historical buildings with complex repair needs.
Significant damage involving custom construction, specialized finishes and a repair scope that needs careful documentation.
A fire claim can involve more than visibly burned materials. Smoke, soot, water used during firefighting and disruption to the property’s use may also need evaluation.
Gather the policy, claim correspondence, available photographs and repair estimates for your review. Coverage and the appropriate next steps depend on the policy and circumstances.
Explore the Free Fire Claim Guide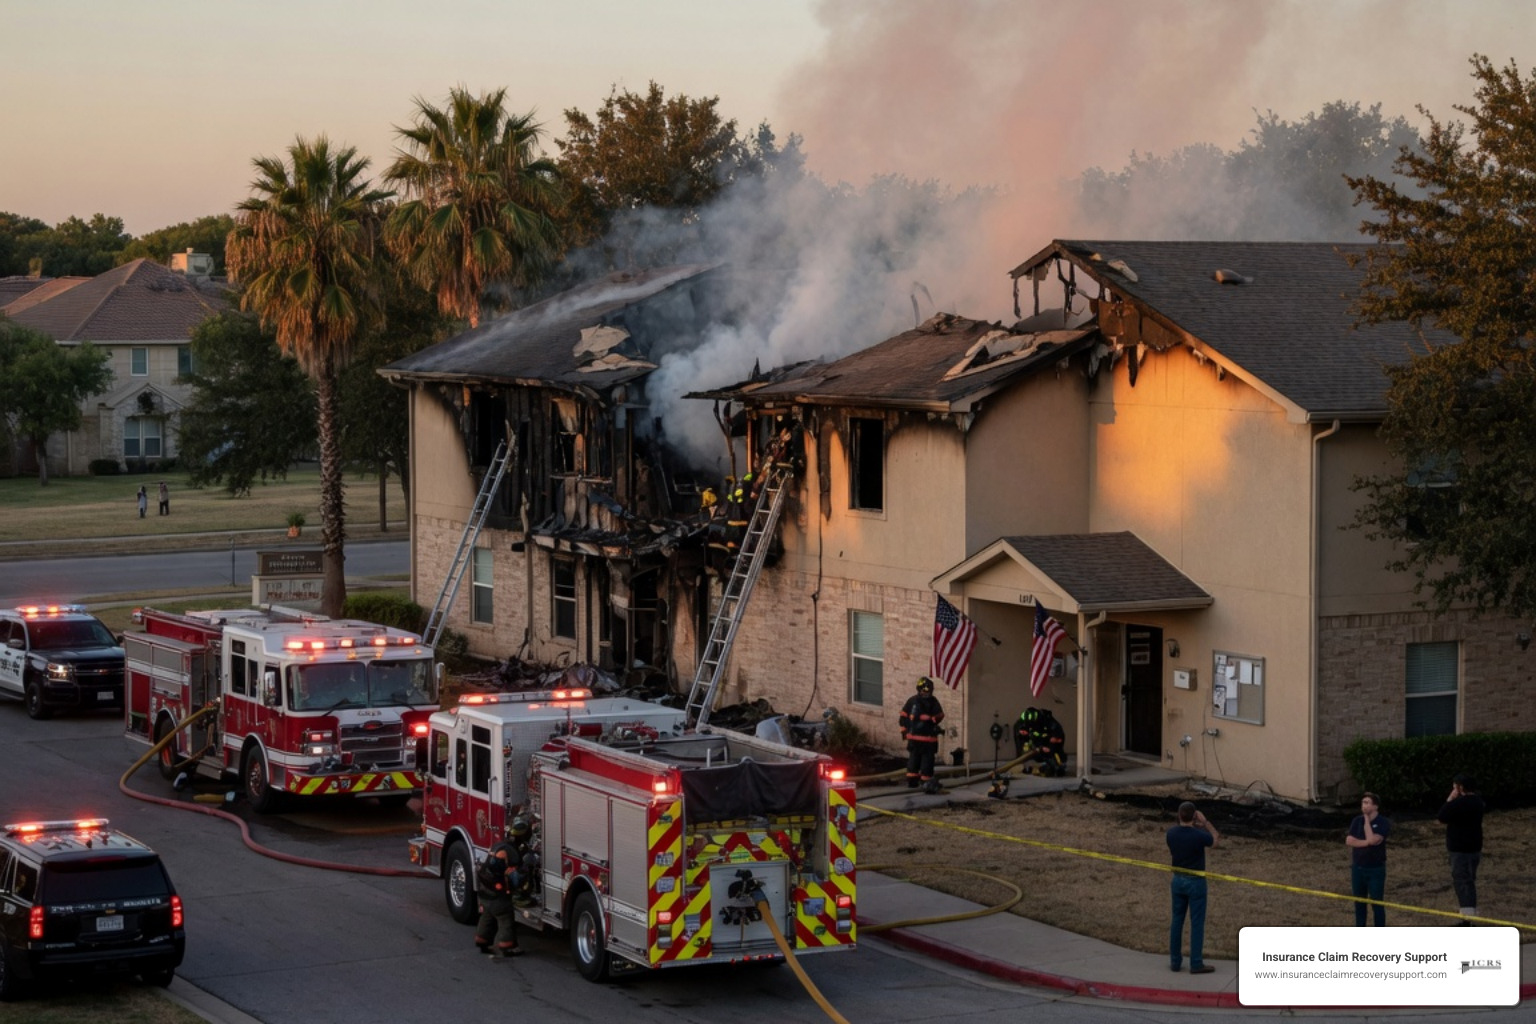
Houston-area claims can involve wind damage, wind-driven rain, a plumbing release or rising floodwater. Record the source and timing separately for each affected building; different coverage forms and deductibles may apply.
Document affected rooms, contents and systems, including firefighting water and questions requiring qualified inspection. Fire and smoke claim support.
Preserve dated roof and exterior photographs, roof-system details, maintenance records and inspection findings. Match each proposed repair to an identified building or roof section. Hail claim support.
Document roof coverings, openings, exterior systems and related interior damage; keep observations tied to the loss date. Wind claim support · Tornado claims · Hurricane claims.
For a pipe burst, photograph the failed section when safe and preserve plumbing reports, mitigation records and affected-unit details. Distinguish that release from roof leaks, wind-driven rain and rising floodwater. Water and burst-pipe claim support.
Retain available weather, heating, occupancy and plumbing records together with the damaged-component evidence. Review resulting water damage separately from the failed pipe or equipment. Winter-storm resources · Freeze and water claims.
Document the water source, entry points, water lines, affected building areas and cleanup records. Review the applicable flood policy separately; property coverage must be checked against its terms. Flood claim support.
Preserve incident records, equipment details, diagnostic findings and repair proposals. Qualified inspection can help distinguish direct damage from unrelated wear or failure. Lightning claim support.
Keep income, expense, tenant, shutdown and restoration-timeline records separate from building estimates. Business interruption is a potential consequence of a loss, not a separate cause of physical damage. Business-interruption claim documentation.
Coverage and recovery depend on the policy, exclusions, deductibles and documented facts. ICRS exclusively represents policyholders. Full representation is for qualifying claims of $250,000+ after deductible. For claims under $250,000, Claim Navigator provides paid strategic guidance, with the option for full representation when appropriate. Request a claim review.


For commercial buildings and apartment complexes, preserve roof and exterior inspections, interior damage photographs, mitigation records and a timeline of the loss. Track shutdowns, affected spaces and supporting financial records separately so any business-interruption questions can be evaluated under the policy.
Start with our Houston commercial and large-loss claim services. For property-specific local information, review Katy, Sugar Land, Cypress, The Woodlands, Tomball or Galveston.
For Pearland, Friendswood or another nearby community, submit the damaged property’s location through the claim-review form. Our team can confirm service availability and the appropriate next step. Keep wind, water-source and repair records organized by location; the city name alone does not establish what a policy covers.
Select the property’s location to explore regional claim resources.
Ready to discuss your loss? Request a claim review through our intake page.
Request a Claim ReviewSee examples of how documented property claims developed after additional scope, evidence and negotiation. Explore ICRS claim results →
These are ICRS portfolio examples; a location in this service area is not asserted.
ICRS documented the building loss and business-interruption components on a 24-unit apartment fire claim. The published case reports a 122% increase, including $1M+ above the insurer offer and $200K+ in business-interruption proceeds.
Read the apartment fire case →ICRS documented roof and interior damage and organized the supporting evidence for a church hail claim. The published case reports a 512% increase without unnecessary litigation.
Read the church hail case →Every claim depends on its policy, facts and documentation. Past results do not guarantee a similar outcome.
Learn who represents you and what to expect from the role.
Read the explanation →Explore the claim process and questions to consider along the way.
Explore the resource →Find additional articles and resources for property owners and managers.
Browse ICRS articles →ICRS is based in Lakeway, Texas and serves property owners in Houston and Katy. This page describes a service area, not a separate Houston and Katy office.
Yes. Share your policy, available estimates and insurer correspondence so the team can review the situation and discuss whether ICRS is a fit.
Our condominium focus is association-level property claims, rather than individual unit-owner claims.
Tell us where the property is, what happened and where the claim stands.
Request a Claim Review
FREE ICRS COMMERCIAL CLAIM RESOURCES
Seven practical PDF guides for commercial and multifamily property owners: the full Resource Kit, the First 72 Hours field guide, four companion checklists, and the 52-jurisdiction source index.
Enter your details below for immediate access to the downloads.
Educational resources only. Requesting the guides does not create a public adjuster engagement or guarantee a claim result. We handle your information under our Privacy Policy.
