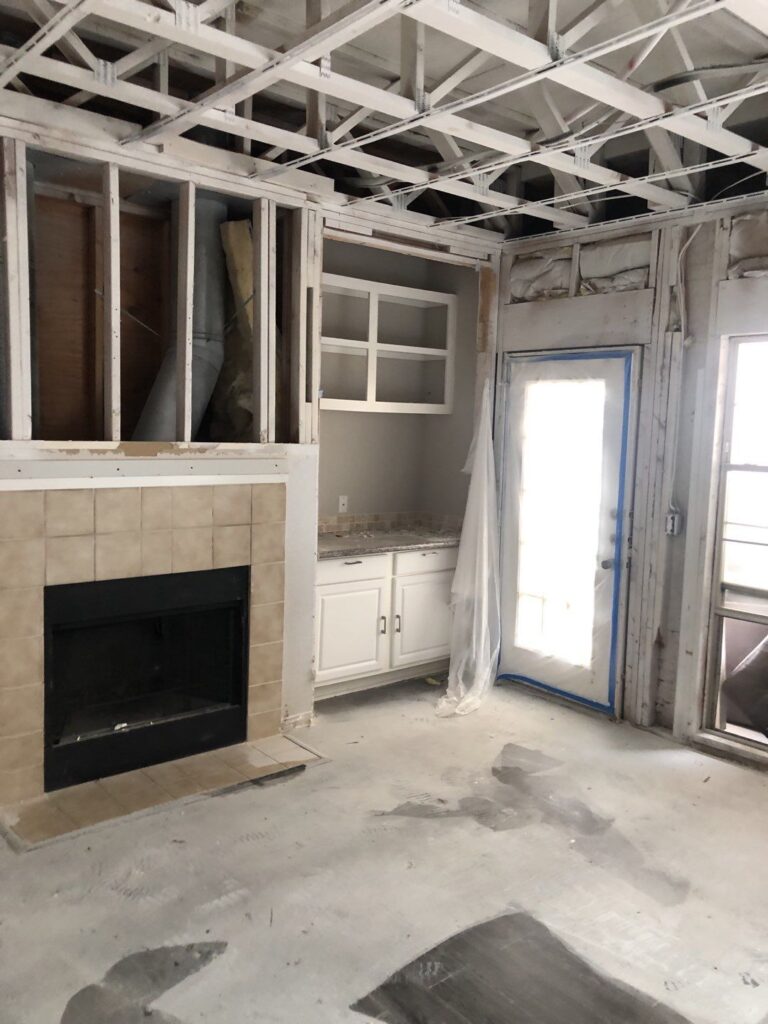
Fire, smoke and soot
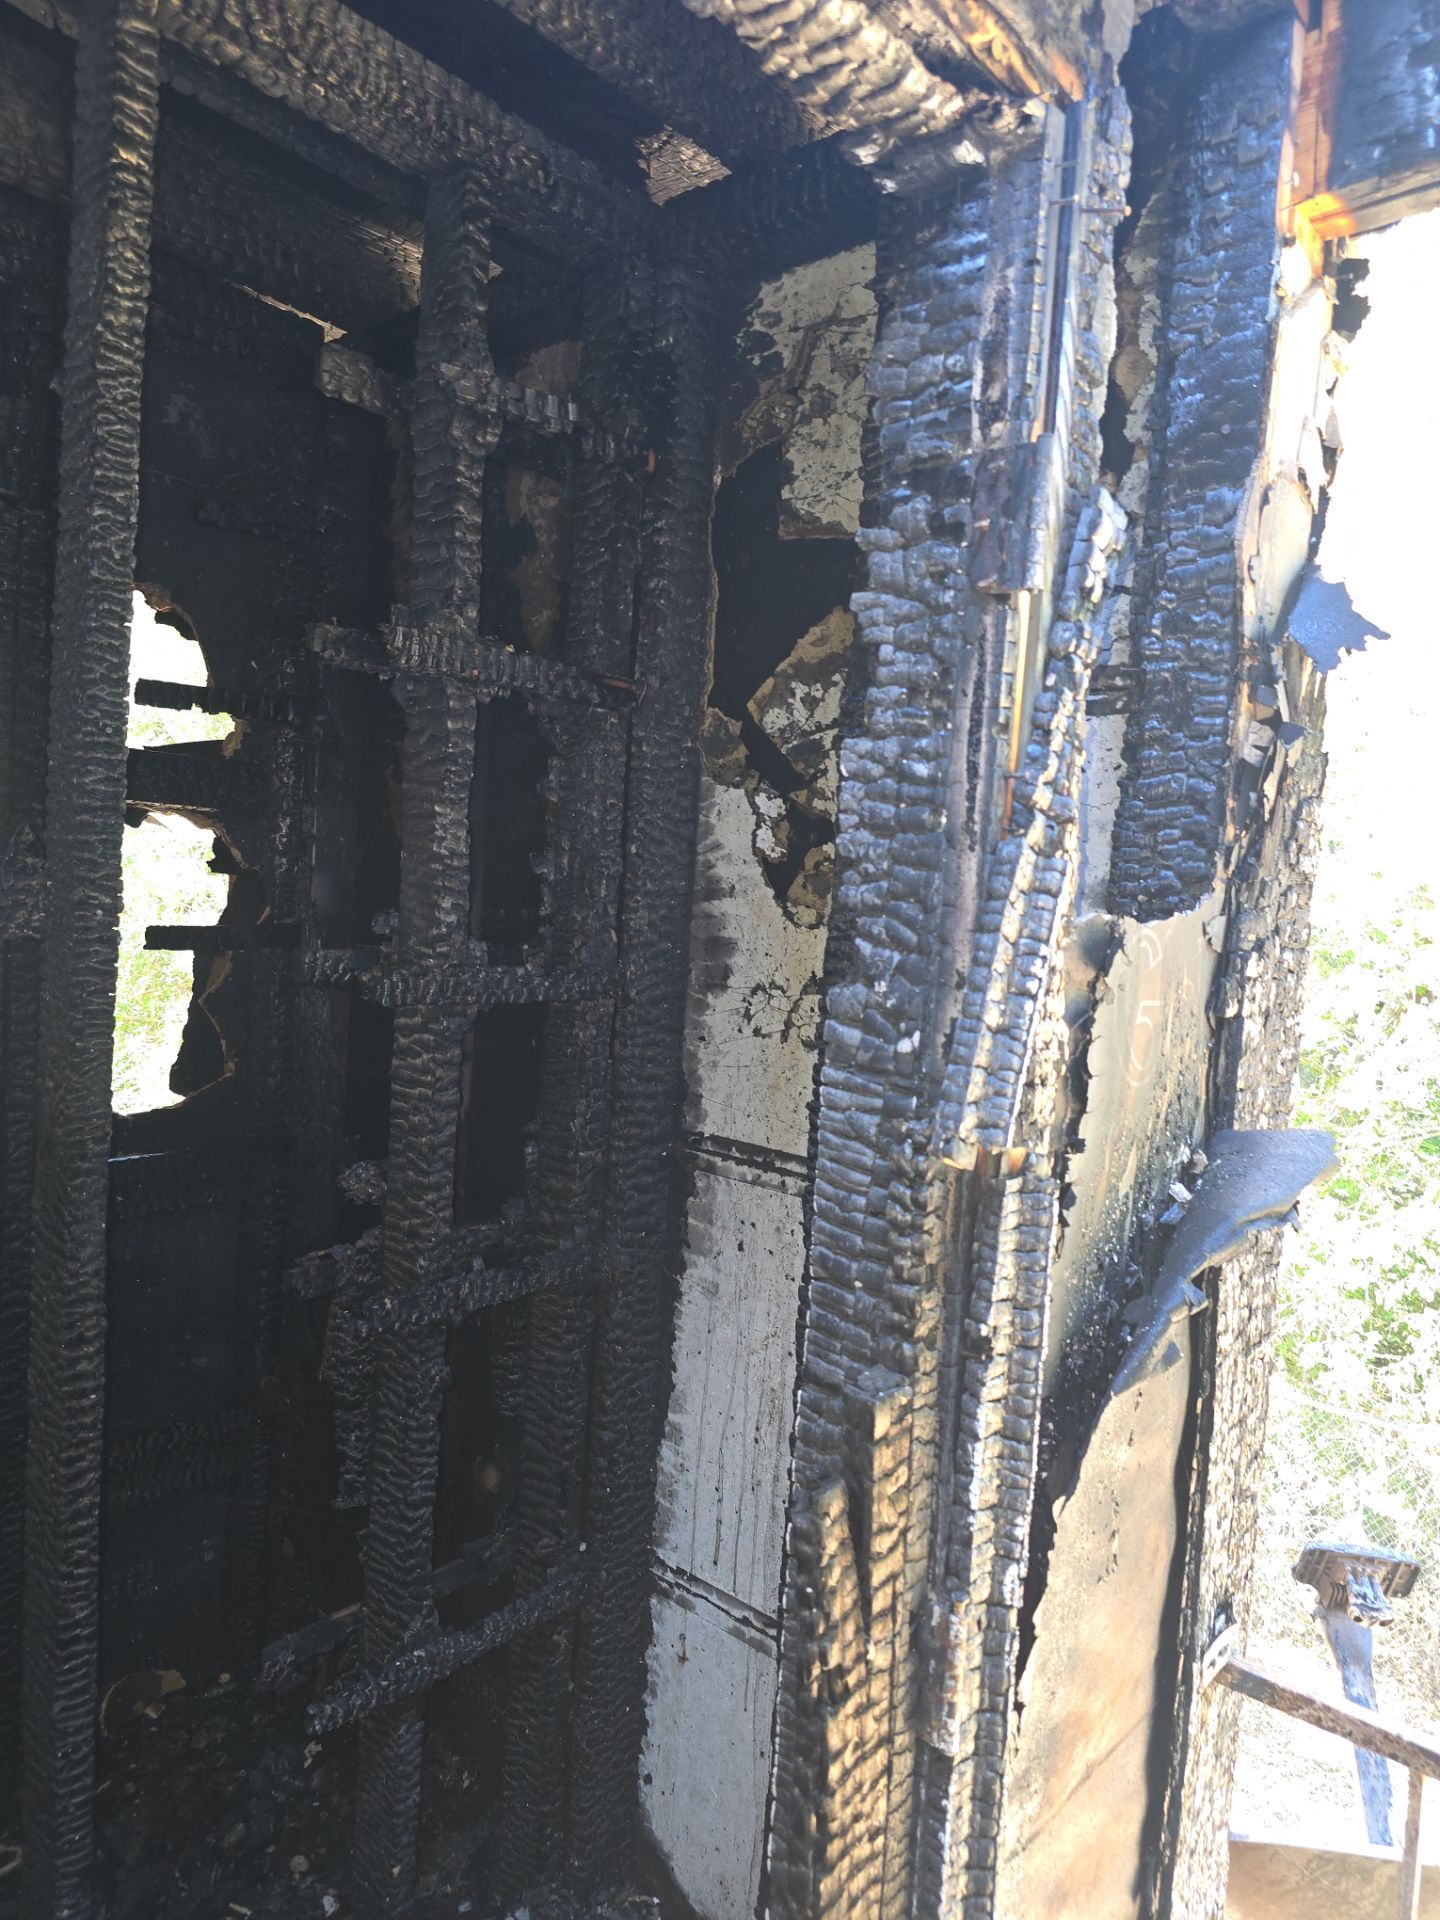
Document affected rooms, contents and systems, including firefighting water and questions requiring qualified inspection. Fire and smoke claim support.
UTAH • POLICYHOLDER REPRESENTATION
ICRS offers full public-adjusting representation for qualifying property claims of $250,000+ after deductible. For claims under $250,000, Claim Navigator provides paid strategic guidance, with the option for full representation when appropriate.
When fire, water, freeze, wind or hail damage threatens commercial property, multifamily buildings, churches, schools or high-value homes in Salt Lake City, Provo and Utah Valley or surrounding Utah communities, ICRS represents your interests—not the insurance company’s. We document the damage, evaluate the loss and negotiate your claim.
Salt Lake City, Utah
Commercial properties · Apartments · Condominium & homeowner associations · Schools · Churches · High-value homes
Call 512-904-9900
When a loss affects multiple building areas, the total in an estimate is only part of the picture. The claim needs a clear account of damaged materials, repair quantities, specialty evaluations, pricing support and payments already received. ICRS works for the policyholder to help document and present that claim and communicate with the insurer.
Share the property address, type of damage, estimated loss size and claim status when requesting a review. Our team will confirm whether the assignment is a fit and discuss the proposed scope of representation and fees before engagement.
Service is arranged around the property location, loss complexity and assignment requirements. Submit the exact address so we can confirm availability and inspection logistics. This page describes a service area; it does not represent a separate office in each city.
Large losses can involve office and retail buildings, industrial properties, apartment communities, condominium and homeowner associations, schools, hotels, churches and high-value homes. Each property needs documentation that reflects its construction and use. For apartments and associations, organize damage by building, unit and common area. For schools, document affected classrooms, equipment and shared facilities, along with repair sequencing and interruptions to use.
For churches, keep sanctuary finishes, seating, sound equipment, mechanical systems and ancillary buildings identifiable in the file. For high-value homes, retain plans, material selections, cabinetry details and records for integrated mechanical, electrical and control systems. For commercial and hospitality properties, keep building costs separate from business-income and extra-expense records.
After a fire, organize observed damage and qualified professional findings by room, material and system. Distinguish confirmed repairs from questions requiring further investigation. For water or freeze losses, retain source-of-loss information, moisture records, mitigation invoices and repair estimates. For wind and hail losses, preserve dated photographs, roof information, maintenance history and inspection findings.
For Salt Lake Valley, Park City, Heber Valley and the northern Utah corridor, claim records should identify the affected structure, room, finish and mechanical system. For seasonal or intermittently occupied buildings, preserve available inspection, occupancy and temperature records.
Document affected rooms, contents and systems, including firefighting water and questions requiring qualified inspection. Fire and smoke claim support.
Preserve dated roof and exterior photographs, roof-system details, maintenance records and inspection findings. Match each proposed repair to an identified building or roof section. Hail claim support.
Document roof coverings, openings, exterior systems and related interior damage; keep observations tied to the loss date. Wind claim support · Tornado claims.
For a pipe burst, identify the reported source, affected levels and rooms, moisture readings and mitigation work. For buildings with specialty finishes or integrated systems, retain the relevant plans and equipment specifications. Water and burst-pipe claim support.
Retain available weather, heating, occupancy and plumbing records together with the damaged-component evidence. Review resulting water damage separately from the failed pipe or equipment. Winter-storm resources · Freeze and water claims.
Document the water source, entry points, water lines, affected building areas and cleanup records. Review the applicable flood policy separately; property coverage must be checked against its terms. Flood claim support.
Preserve incident records, equipment details, diagnostic findings and repair proposals. Qualified inspection can help distinguish direct damage from unrelated wear or failure. Lightning claim support.
Keep income, expense, tenant, shutdown and restoration-timeline records separate from building estimates. Business interruption is a potential consequence of a loss, not a separate cause of physical damage. Business-interruption claim documentation.
Coverage and recovery depend on the policy, exclusions, deductibles and documented facts. ICRS exclusively represents policyholders. Full representation is for qualifying claims of $250,000+ after deductible. For claims under $250,000, Claim Navigator provides paid strategic guidance, with the option for full representation when appropriate. Request a claim review.
Coverage and the appropriate scope depend on the policy and evidence. A damage description alone does not establish coverage or justify replacing every component.
Use our large-loss documentation checklist. You can also review our commercial claim services, fire claim services and water damage claim resources.
For churches, apartments, HOAs, schools and commercial properties, documenting roof damage and related interior damage helps establish the full claim scope. Explore our published church hail claim case example and learn how ICRS represents policyholders. Review What Is a Public Adjuster?, selected ICRS claim results (results vary), our fire damage claim services, and the fire insurance claim guide.
Explore published ICRS portfolio examples: multifamily freeze and water damage and an apartment fire insurance claim. Review the documented scope, claim issues and outcome described in each case.
Prepare your property records with our large-loss documentation checklist. These portfolio examples are not identified as Utah claims. Every claim depends on its policy, facts and evidence; past results do not guarantee a similar outcome.
The video below explains how ICRS represents policyholders and approaches substantial property insurance claims.
Whether your claim is newly reported or you are comparing an insurer’s estimate with a substantially larger documented scope, start by sharing the current file. ICRS exclusively represents policyholders.
Request your property claim review · 512-904-9900 · admin@insuranceclaimrecoverysupport.com

FREE ICRS COMMERCIAL CLAIM RESOURCES
Seven practical PDF guides for commercial and multifamily property owners: the full Resource Kit, the First 72 Hours field guide, four companion checklists, and the 52-jurisdiction source index.
Enter your details below for immediate access to the downloads.
Educational resources only. Requesting the guides does not create a public adjuster engagement or guarantee a claim result. We handle your information under our Privacy Policy.


Your property. Your investment. Your recovery. Get a practical guide to documenting damage, understanding your claim and asking better questions after a fire, storm or other major loss.
Enter your first name and email. No account or password required.
Insurance Claim Recovery Support represents policyholders, never insurance companies. Requesting this report does not create an adjuster-client relationship or guarantee coverage or recovery.
Join our mailing list to get the latest updates, news and special offers delivered directly to your inbox.
Enter your email to receive this free ICRS guide, practical claim checklists, and ongoing ICRS educational emails, typically weekly. You can unsubscribe at any time.
Looking for help with a specific loss? Explore the free Fire Claim Guide or Water Claim Guide.
Request a Free Large-Loss Claim Review ($250,000+ after deductible).