Commercial buildings
Offices, retail, hospitality, industrial, religious, school, and other commercial properties with complex repair scopes.
Commercial claim support →
When a large building or several structures are damaged, scattered photographs and estimates can make the claim harder to evaluate. Insurance Claim Recovery Support, LLC (ICRS) represents policyholders and helps document, present, negotiate, and settle complex property insurance claims.
Serving apartment complexes, commercial roofs, schools, churches, and industrial facilities.
Request a Claim ReviewBased in Lakeway, Texas · Serving policyholders in Lubbock
After a major loss, property owners and managers must protect people and the building while keeping records, coordinating vendors, and responding to the insurer. Starting with a clear record can reduce confusion about what was damaged and what the claim includes.
ICRS is a licensed Texas public adjuster agency. We represent policyholders, not insurance companies. We review the facts, help develop a supportable scope, and pursue a fair resolution through the claim process.
What is a public adjuster? →For each affected building, record the roof type, observed damage, inspection date, interior conditions, and available maintenance records. Keep photographs and estimates tied to the same building names so the claimed scope can be reviewed coherently.
See how ICRS works →Offices, retail, hospitality, industrial, religious, school, and other commercial properties with complex repair scopes.
Commercial claim support →Apartment communities, condominium properties, HOAs, and multiple-building claims requiring organized evidence.
Multifamily claim support →Significant losses involving custom construction, specialty materials, or extensive damage.
Explore property types →For Lubbock schools, churches, apartments, warehouses and commercial properties, keep roof and building inventories aligned with the loss documentation. Alongside hail and wind, ICRS reviews qualifying fire, water, pipe-burst and freeze claims.
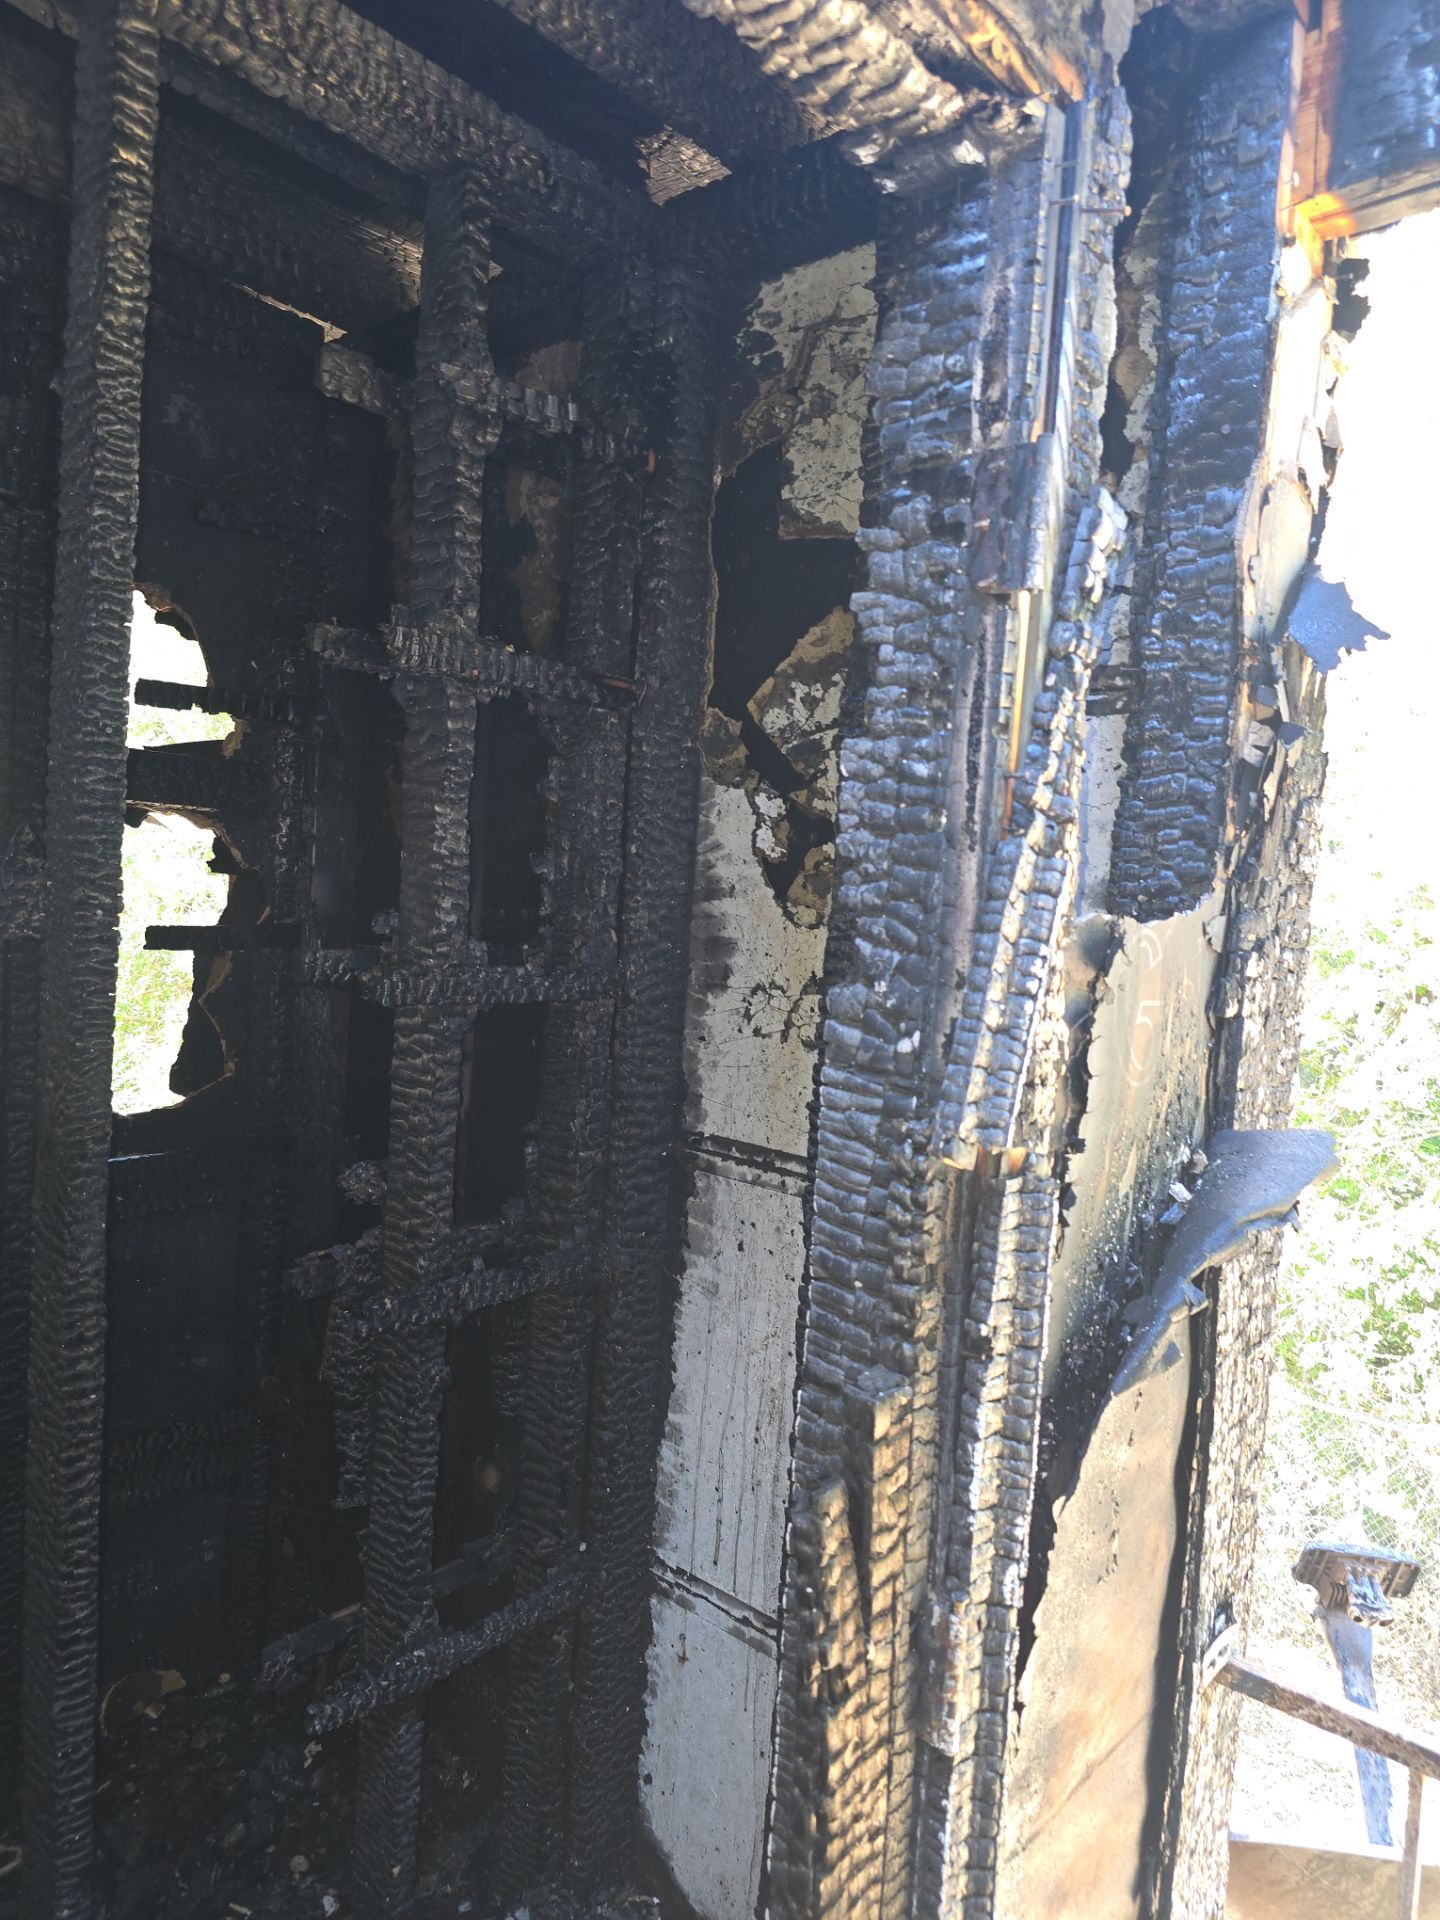
Document affected rooms, contents and systems, including firefighting water and questions requiring qualified inspection. Fire and smoke claim support.
Preserve dated roof and exterior photographs, roof-system details, maintenance records and inspection findings. Match each proposed repair to an identified building or roof section. Hail claim support.
Document roof coverings, openings, exterior systems and related interior damage; keep observations tied to the loss date. Wind claim support · Tornado claims.
For a burst pipe or water release, record the source, discovery date, affected interiors and emergency work. Label rooms and buildings consistently so moisture findings and repair estimates can be compared. Water and burst-pipe claim support.
Retain available weather, heating, occupancy and plumbing records together with the damaged-component evidence. Review resulting water damage separately from the failed pipe or equipment. Winter-storm resources · Freeze and water claims.
Document the water source, entry points, water lines, affected building areas and cleanup records. Review the applicable flood policy separately; property coverage must be checked against its terms. Flood claim support.
Preserve incident records, equipment details, diagnostic findings and repair proposals. Qualified inspection can help distinguish direct damage from unrelated wear or failure. Lightning claim support.
Keep income, expense, tenant, shutdown and restoration-timeline records separate from building estimates. Business interruption is a potential consequence of a loss, not a separate cause of physical damage. Business-interruption claim documentation.
Coverage and recovery depend on the policy, exclusions, deductibles and documented facts. ICRS exclusively represents policyholders. Full representation is for qualifying claims of $250,000+ after deductible. For claims under $250,000, Claim Navigator provides paid strategic guidance, with the option for full representation when appropriate. Request a claim review.
Hail and wind can damage roof and exterior systems; fire and water losses can add interior and operational impacts. ICRS helps present the documented claim.
Fire claims can include smoke, soot, firefighting water, and interruption to the property’s use. Storm claims may require careful review of roof, exterior, and interior damage. Coverage depends on the policy and the facts of the loss.
Fire damage claims · Hail claims · Wind claims · Water claims
Explore the Free Fire Claim Guide
The best time to involve a public adjuster is often early, before the claim scope becomes confused or incomplete.
Review selected ICRS claim results and examples of documented fire, hail, and commercial property losses. Each result depends on its own policy, facts, and supporting evidence.
Explore documented claim results →
Watch the ICRS corporate video →
Past results do not guarantee the outcome or timing of another claim.
For a school, church, warehouse, or apartment community, a roof claim can involve several roof types and building uses. Document each roof separately, along with flashing, rooftop equipment, ceilings, and any interior water damage. Keep inspection dates and photographs tied to a labeled roof plan where possible.
Emergency work and permanent repair proposals serve different purposes. Preserve both, along with the insurer’s estimate and any engineering or contractor observations, so the claim scope can be reviewed on a common set of facts. For another West Texas service area, visit the Amarillo claim page.
ICRS is based in Lakeway, Texas and serves policyholders in Lubbock. This page describes a service area, not a separate local office.
Yes. Share available estimates, insurer correspondence, and the current claim status. ICRS can discuss whether its services fit the loss and stage of the claim.
No. ICRS represents policyholders in property damage insurance claims.
Tell us what happened, where the damaged property is, and where the claim stands.
Request a Claim ReviewOr call 512-904-9900. Insurance Claim Recovery Support, LLC · Texas public adjuster agency license #1670060 · NPN #16144334.
FREE ICRS COMMERCIAL CLAIM RESOURCES
Seven practical PDF guides for commercial and multifamily property owners: the full Resource Kit, the First 72 Hours field guide, four companion checklists, and the 52-jurisdiction source index.
Enter your details below for immediate access to the downloads.
Educational resources only. Requesting the guides does not create a public adjuster engagement or guarantee a claim result. We handle your information under our Privacy Policy.