

vijay
5 months ago
Scott and Misty with Insurance Claim Recovery Support are outstanding. As a multifamily owner, I have used them numerous times on insurance claim matters, and they have consistently delivered excellent, prompt results.
They are knowledgeable, responsive, and very effective at helping navigate the claim process from start to finish. Their attention to detail, professionalism, and PERSISTENCE have made a real difference in the outcome of our claims. They understand the issues property owners face and know how to properly document and present a claim.
I highly recommend Scott, Misty, and Insurance Claim Recovery Support to any property owner needing help with an insurance claim. They are experienced, trustworthy, and results-driven.
Vivian Williams
1 year ago
Our experience with ICRS was a five star experience ; we received more money than what the insurance company had offered for an apartment fire, plus we recieved money that we thought we would not get. GREAT JOB.
Sign : Cornell Williams
Dallas Rice
1 year ago
Scott and his entire team so incredibly knowledgeable, their is no way we could have accomplish what we did without their guidance. Keep us the great work!!!!!
Ashley Szulim-Sabean
2 years ago
They are truly a Lifesaver!
I cannot say enough good things about Insurance Claim Recovery Support — they truly feel like earth angels. Misty and Scott helped me through one of the most overwhelming and helpless times of my life. As a single woman dealing with major home renovations after a severe water leak, I was unfortunately taken advantage of by a dishonest contractor. From breaking my TV and not saying a word, to lying about repairs, damaging my sprinkler, inflating estimates with bogus charges, and even threatening legal action — I was completely overwhelmed.
That’s when Misty and Scott stepped in. Their knowledge of the laws and the insurance claims process is unmatched, and their compassion and support were exactly what I needed. They knew exactly how to handle the situation, empowered me with the facts, and guided me every step of the way. They genuinely listened, made me feel heard and understood, and stood by my side when I needed it most. I am beyond grateful for their integrity, expertise, and kindness. If you’re facing a tough insurance claim situation, do not hesitate to reach out to them — they are absolute professionals and true advocates and helped me feel safe in my own home again.
AdiMak2004
2 years ago
I spoke with Scott about a commercial claim, and he was incredibly helpful. He provided detailed explanations about how policies and adjustments work, making everything much clearer. I really appreciated his thoroughness and knowledge!
Case Wegner
2 years ago
After a nightmare experience dealing with an underpaid commercial property insurance claim from a hailstorm in Dallas, we were fortunate enough to find Scott and Misty Friedson at Insurance Claim Recovery Support (ICRS). Had we not hired them, we would’ve left $127,000 on the table - money we didn’t even know we were owed.
Scott and Misty are absolute professionals. Their knowledge of the insurance claim process is unmatched, and they navigated our case with skill, integrity, and relentless attention to detail. On top of that, they’re HAAG certified roof inspectors, which made all the difference in proving the true extent of our damages.
Looking back, we wish we had hired ICRS from the very beginning. It would have saved us so much stress, time, and lost money. If you’re dealing with an insurance claim - especially a commercial one - don’t wait. Call ICRS.
We’re beyond grateful for everything they did for us.
Jason Cheshire
2 years ago
ICRS has been a beacon of hope during one of the most challenging times in my life. After my home was struck by lightning nearly nine months ago, dealing with USAA has been nothing short of a nightmare. They have grossly underpaid my claim, and I was at my wit’s end after countless hours of research, discussions with attorneys, and trying to figure out how to rebuild my home without compromising my financial future.
Scott and Misty from ICRS have been the most honest, supportive, and knowledgeable people I’ve encountered throughout this ordeal. They made me feel heard and understood, which was a welcome relief after so many interactions with professionals who seemed more interested in their bottom line than in helping me.
Scott guided me through this incredibly complex and stressful process with expert advice, giving me the clarity and confidence I desperately needed. His and Misty’s commitment to doing what’s right for their clients is unmatched. They genuinely care and provide guidance and support that feels personalized and sincere.
Thanks to Scott and Misty, I’m back on track and no longer feel overwhelmed. ICRS has saved me countless hours of stress and struggle, and I wholeheartedly recommend them to anyone dealing with a large-loss claim after a storm. Trust me—making them your first call can save you immeasurable frustration and help you navigate this difficult path with sound advice and unwavering support.
Thank you, Scott and Misty, for everything you’ve done!
-Jason Cheshire

Tom Chisano
2 years ago
Found this firm very responsive with honest advice. Based on our discussion, I actually did not hire them, at least yet, because my claim doesn't require the service. They easily could have pushed to sign me up, but did not. We have just gone thru flooding of our home and it is appreciated not being taken advantage of now.

Albert Prien
3 years ago
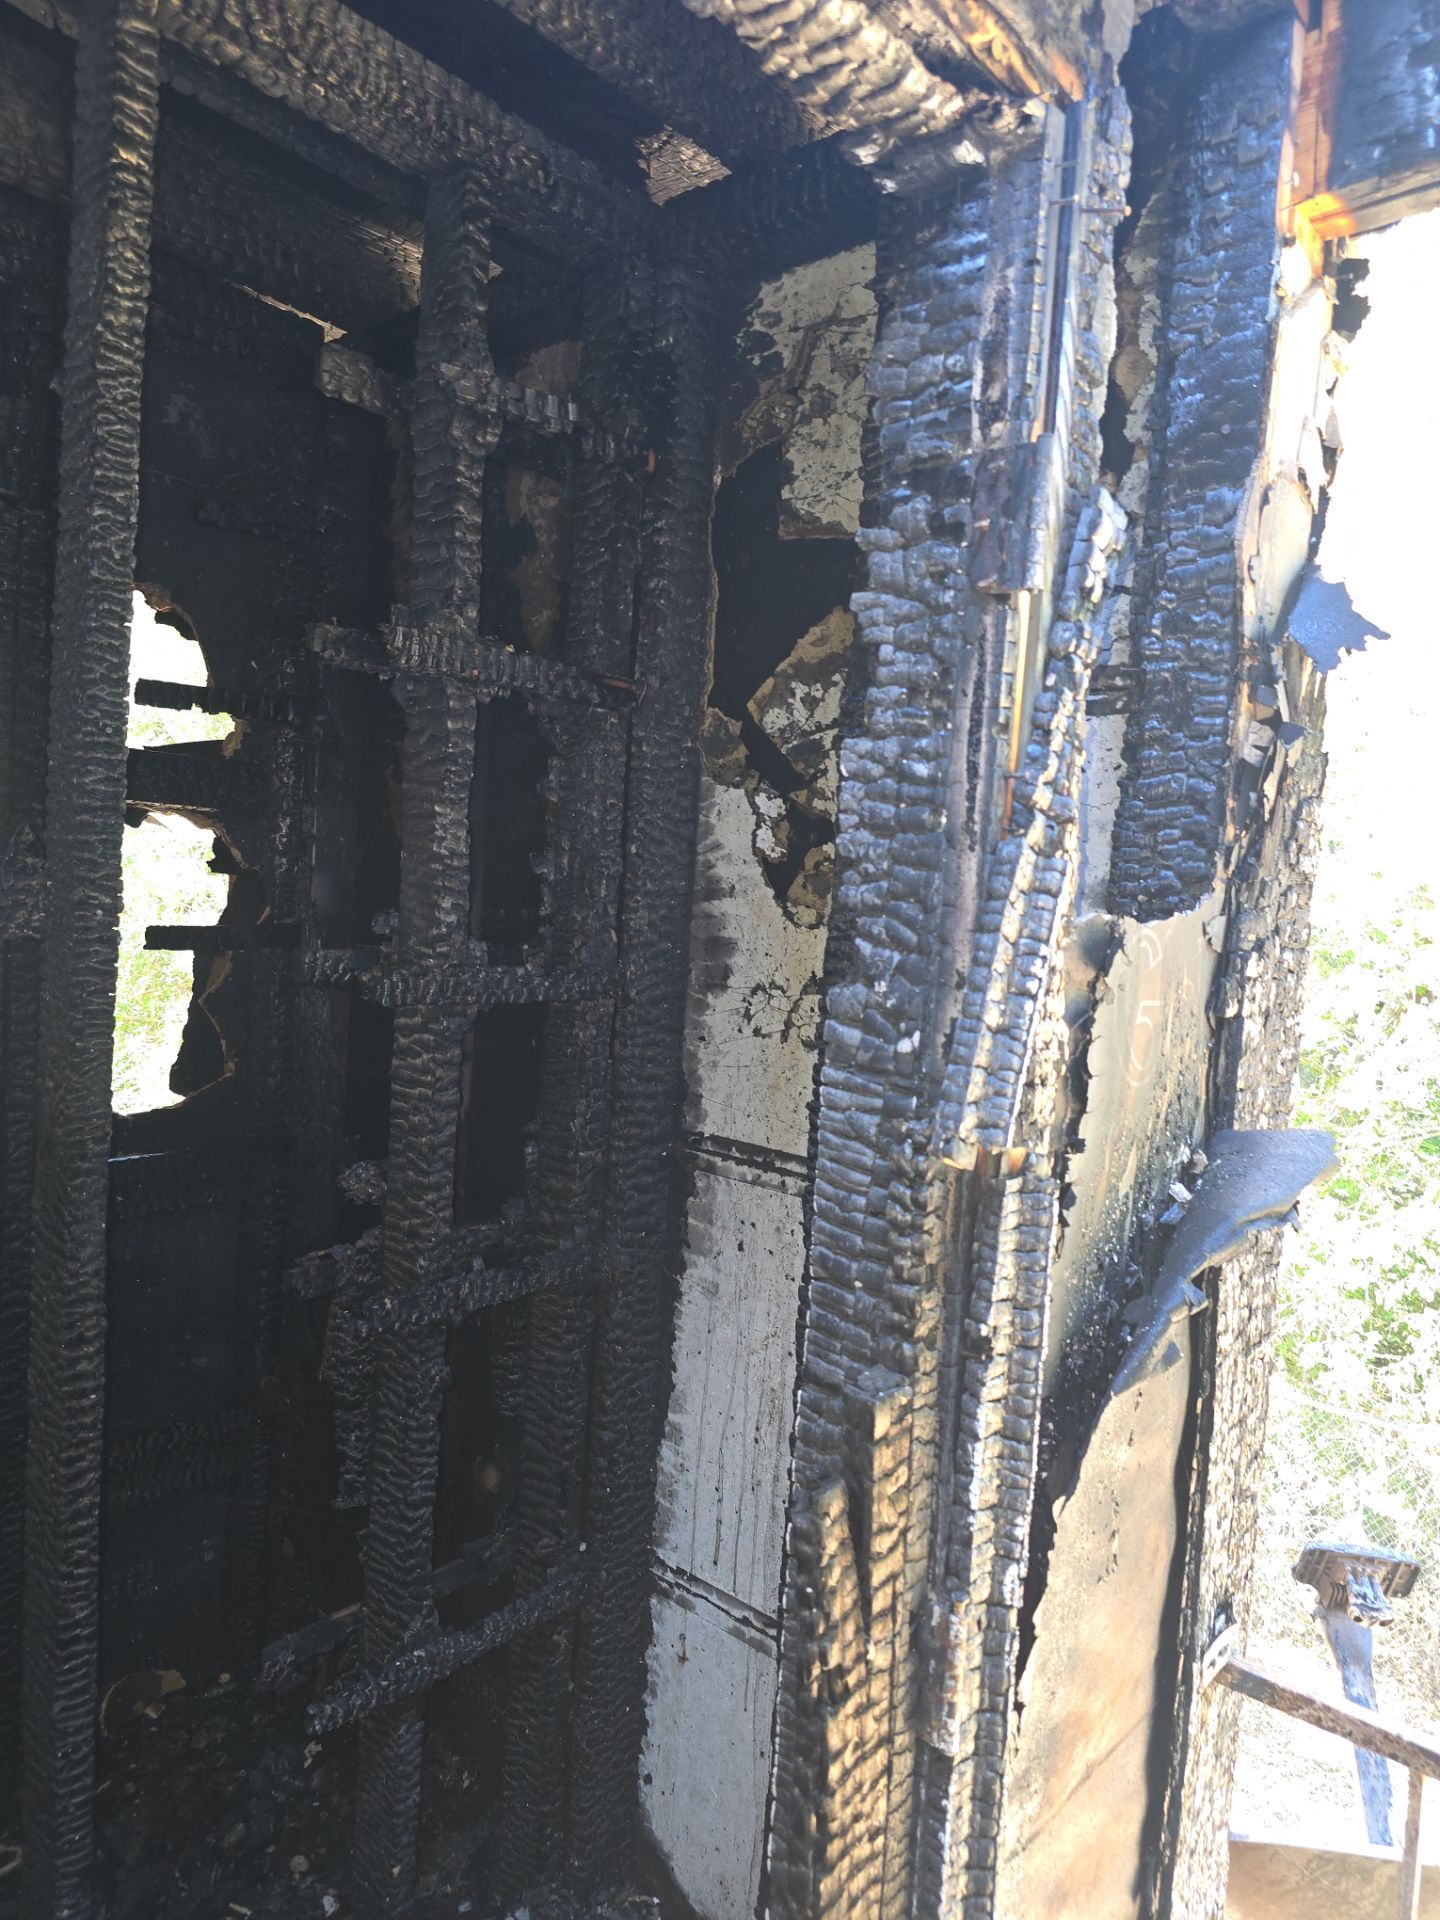
In 2023, our family woke up to a nightmare. Our house was filled with smoke and on fire. We able to get our son and pets out of the burning house without injury, and our local fire department arrived quickly and put out the fire. By the time that the fire was out, most of our home was destroyed. We contacted our insurer to start a claim and were immediately met with opposition and confusion on their part. It took several weeks for them to assign an adjuster to our claim. This initial experience led our decision to hire a Public Adjuster to navigate the process and advocate on our behalf. We couldn’t trust that our insurer would handle the claim responsibly, and we quickly realized that we needed someone to fight for us to hold them accountable to our policy. We were extremely fortunate to find ICRS and secure Scott as our Public Adjuster.
Our Insurer mislead us and withheld information. It took weeks for them to provide a copy of our policy, and when they did, they excluded information that benefited us. ICRS pressured them to provide a full copy of our policy which included the benefits they had initially excluded.
Our Insurer provided a scope that was not aligned with the actual cost of rebuilding our home. ICRS countered with a realistic scope and advised us to secure independent quotes on our own. ICRS then leveraged its scope and the independent quotes to force our insurer to provide more realistic amount for the rebuild. The scoping process took months, and ICRS drove the communications the entire time.
The first adjuster that our insurer assigned to our claim arrived at the site visit and interview with a combative attitude, where he used inappropriate language, and attempted to force the negotiations their favor by manipulating the facts. ICRS swiftly called out the adjuster and guided the negations back on track.
Our Insurer cycled through four adjusters during our claim. The pass-down of information between these adjusters was insufficient, with each new adjuster attempting to avoid payout using the same methods that failed with the last. We were astonished that a company could act in this manner without serious recourse. ICRS was able to leverage emails, photos, inspection reports, and additional documentation to bring the adjusters up to speed after each transition. ICRS’ efforts kept the claim moving every time our insurer attempted to stall.
When our Insurer misrepresented the policy and refused to pay out for damages that were covered, ICRS drove the communications process and provided documentation, which included case-law excerpts from similar claims that had gone to trial. This approach provided breakthroughs on vital areas of the negotiations. ICRS provided a paper trail and documentation that our Insurer couldn’t ignore, and ultimately they were forced to pay out due to the exposure that ICRS had made apparent.
ICRS increased the overall claim by more than 20% during the planning and rebuild process through supplements. Through negotiations with our Insurance company, ICRS increased the claim by 104% over what was released up-front in our initial settlement. Additionally, the payout ICRS secured for us was 31% higher than our policy limit.
Before that fire, we had heard insurance companies pull out every trick in the book to avoid paying out on a policy. Having gone through this experience, we can say that the behavior on our insurers part was far worse than we had ever imagined possible. We advise with 100% conviction that anyone dealing with a large loss such as ours, hire a public adjuster to navigate and advocate on their behalf in order to get the needed results. Our family could not have rebuilt our home with the funds our insurance company provided, and we only have a home to return to because of ICRS’ efforts to hold our insurer accountable for the policy we had paid for. Throughout the claim, which lasted over a year, ICRS navigated the entire claim process with professionalism and care. Our family offers a sincere thank you to Scott, Misty, and the entire ICRS team.

Sue Edwards
3 years ago
ICRS is phenomenal! They walked us through all the loops we needed to jump through. They went to bat for us when we weren't even sure we were in the game! Thank you Misty and Scott! We are more appreciative than we can put into words!
Julie Bug
3 years ago
I definitely recommend ICRS! Scott and Misty went above and beyond to advocate on our behalf and help us navigate the nightmare of a large loss insurance claim. Scott has worked as a public adjuster for more than 15 years. He was extremely knowledgeable about the process, laws, and holding the insurance company accountable. The initial amount the insurance company agreed to would not have been enough to restore our property, and Scott negotiated to maximize our claim.

April Parker
3 years ago
Hands down the absolute best customer service, always responsive, knowledgeable and always eager to help!

Bobby Davis
3 years ago
Very knowledgeable and helped me through an insurance nightmare. Look no further.

DeeDee Ritzinger
3 years ago
Scott is extremely knowledgeable and competent. He assisted and provided direction enabling me to improve my claim. I highly recommend Scott and his company, ICRS.

Ericka Wood
3 years ago
Extremely helpful and friendly.
Very knowledgeable. Thank you for helping!!

Ken Culotta
4 years ago
ICRS was very helpful to our condo association in connection with our recent property damage claim settlement. We are not insurance pros, but when some aspects of the insurer’s settlement offer did not appear to match up with our asessment of damage, ICRS helped us understand what further claims of damage were realistic and helped us achieve success on those claims.

James Matthew
5 years ago
Words can’t describe how grateful we are for the consultation and claim evaluation we had with Scott. Full disclosure we were unable to work with him due to limitations of our scope. We wanted to properly recognize Scott for the honest and genuine passion he put in to not only our claim, but the way he runs his business in general. We hadn’t had such clarity of next steps since this began in 2020. I would highly recommend this business to everyone spinning their wheels in this process!

Haidee Jugmans
5 years ago
Scott responded to my inquiry and took the time to listen and understand our unpleasant experience dealing with our insurance claim. Although I did not utilized his service, he gave me a sound, professional advice and offered to help when he referred me to his engineer. They replied promptly and I was able to have better understanding of the situation. Thank you Scott!

Katie Hollis
6 years ago
This was not the first public adjuster I called. I called a different company first but they gave me a bad feeling on the phone. Too aggressive. Didn't feel trustworthy to me. So, I kept looking. I came across this company and I had none of those bad feelings. Scott, the guy who took my call, seemed very knowledgeable and I felt I could fully trust him. As it turned out, he told me that my claim was fairly simple and I didn't need the full scope of his service and fees. But, without charging me a fee, he gave me some needed advice on this whole matter of insurance claims which I needed. And told me I could call him back to ask another question or two if necessary. I would recommend this company for these services.