Updated November 3, 2026 · By Scott Friedson, ICRS
Public Adjuster Claim Process: The Main Steps
A public adjuster helps a policyholder document, value, present, and negotiate a property insurance claim. This guide explains what to expect from the initial review through resolution. Services and responsibilities depend on the written agreement and applicable law.
Start with what a public adjuster does, or review public adjuster fees, Texas limits, and ICRS’s fee example.
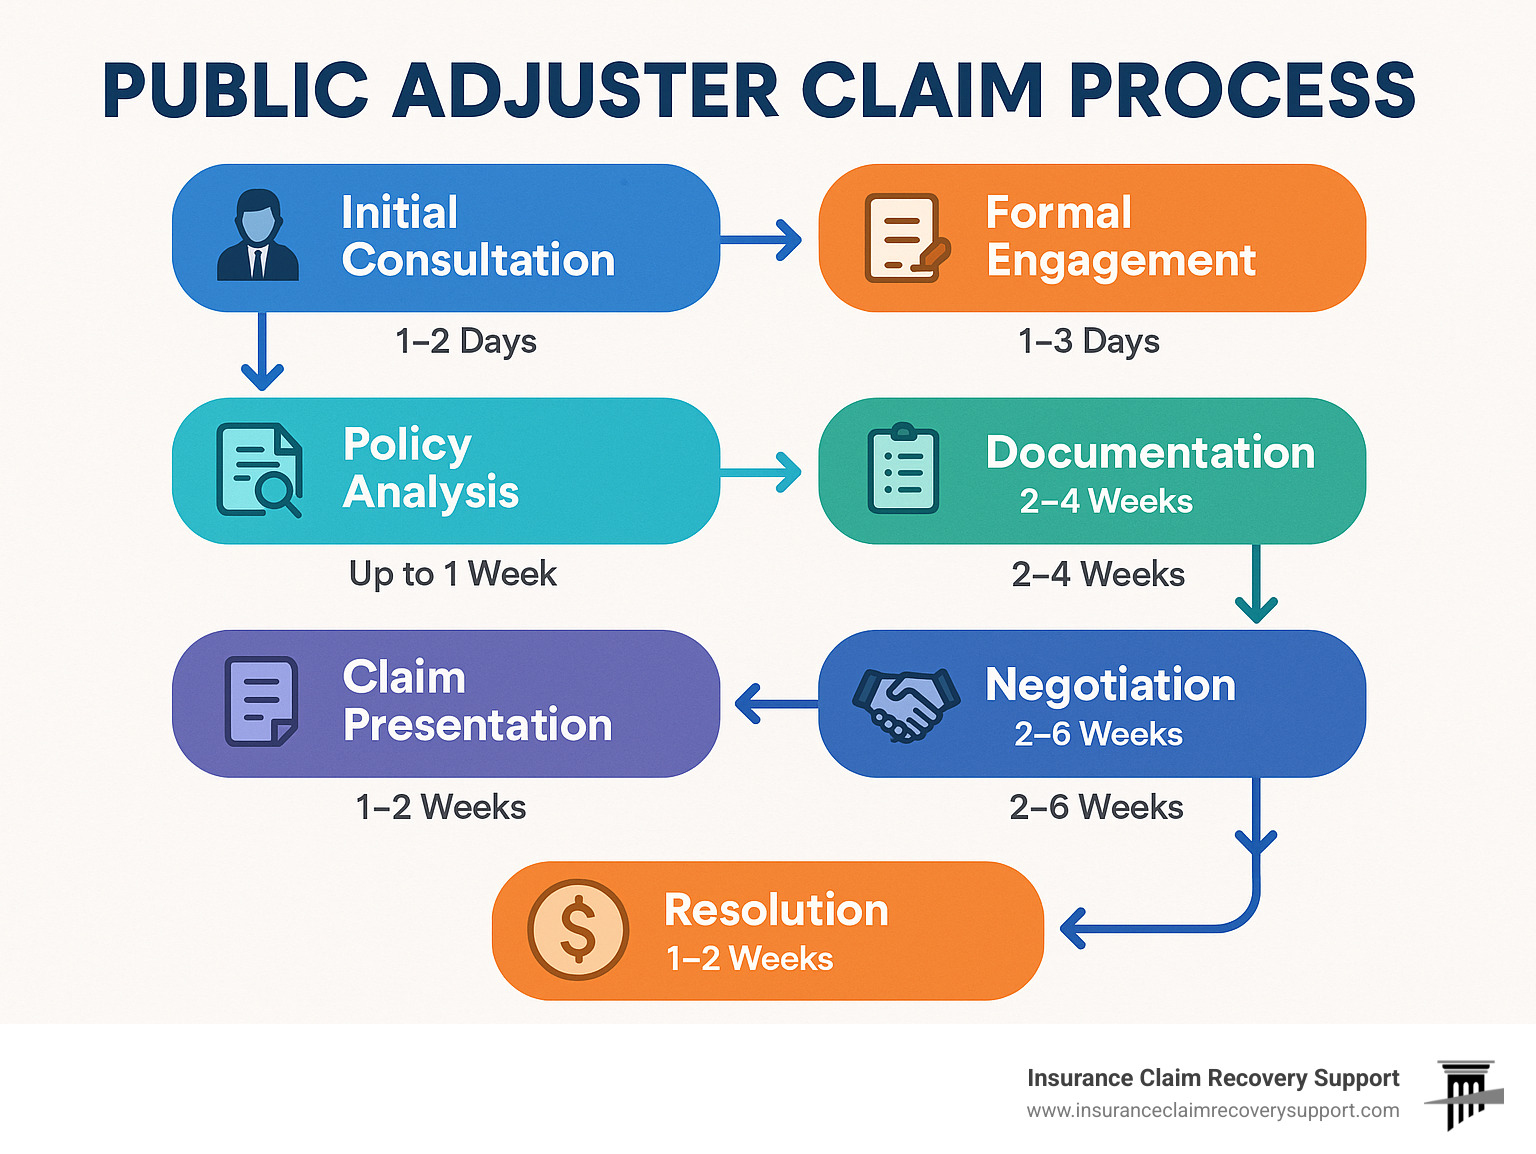
The public adjuster claim process typically follows these key steps:- Initial claim review – Assessment of the loss, claim status, and service fit
- Formal engagement – Signing representation agreement
- Policy analysis – Reviewing coverage details and exclusions
- Documentation – Gathering evidence and preparing estimates
- Claim presentation – Submitting formalized documentation to insurer
- Negotiation – Advocating for maximum settlement
- Resolution – Finalizing settlement and disbursement
“You’re just traumatized when you have these losses. At some point, you’re just glad you’re alive. And then you have to turn to the business side of this. It’s tough.” — Don Hornstein, University of North Carolina insurance law expertA public adjuster can help identify and document supported losses and explain the claim process. The outcome depends on the insurance policy, damage, evidence, and claim circumstances. Hiring a public adjuster does not guarantee a larger settlement. I’m Scott Friedson, a multi-state licensed public adjuster who has settled hundreds of millions in commercial and multifamily property damage claims throughout my career working through the public adjuster claim process for over 500 large losses valued at more than $250 million.
 Public adjuster claim process definitions:
– Hail storm insurance claim
– assistance with insurance claims
– insurance claims dispute assistance
Adjuster 101: Company vs Independent vs Public
When your property suffers damage and you file an insurance claim, you’ll soon meet an insurance adjuster – but did you know there are three distinctly different types? Understanding these differences is crucial before diving into the public adjuster claim process. Think of insurance adjusters as the people who determine how much money you’ll receive for your claim. But here’s the catch – they don’t all work for the same team.| Type | Who They Work For | Who Pays Them | Primary Goal |
|---|---|---|---|
| Company (Staff) Adjuster | Insurance Company | Insurance Company | Minimize Claim Payout |
| Independent Adjuster | Insurance Company | Insurance Company | Minimize Claim Payout |
| Public Adjuster | Policyholder | Policyholder | Maximize Claim Recovery |
Company (Staff) & Independent Adjusters Explained
Company adjusters are direct employees of your insurance carrier. They receive regular paychecks, benefits, and often performance bonuses tied to how well the company performs financially. Their career advancement depends on keeping their employer – the insurance company – happy with their work. “Wait, what about independent adjusters? Aren’t they… independent?” Not exactly. Despite their somewhat misleading name, independent adjusters still work for insurance companies – just as contractors rather than employees. Insurance carriers typically bring them in during disasters when they need extra hands to process many claims quickly. As Charles Nyce, a risk management professor at FSU, points out, “About 90 percent of all insurance claims are settled without escalating into a court fight,” but that doesn’t mean these settlements are always fair or complete. Both company and independent adjusters share a common focus: controlling costs for the insurer. While many are ethical professionals, their primary duty is to their employer – not to you. They’re looking at your claim through the lens of company policies, procedures, and bottom lines.What Makes a Public Adjuster Different
Public adjusters stand alone as the only licensed insurance professionals who work exclusively for you, the policyholder. This fundamental difference creates a true fiduciary relationship – they’re legally obligated to put your financial interests first. Amy Bach, executive director of United Policyholders, explains it perfectly: “The insurance companies have totally the upper hand and when there’s a public adjuster, it does level the playing field a lot for the consumer having someone who speaks insurance and speaks damage.” Unlike the other types, public adjusters:- Are licensed by state insurance departments
- Must pass rigorous professional exams
- Maintain ongoing continuing education
- Adhere to strict ethical standards
- Have a fiduciary duty to policyholders
Is Hiring a Public Adjuster Right for You?
Not every insurance claim requires a public adjuster, but certain situations strongly warrant professional representation. Understanding when to engage a public adjuster can significantly impact your claim outcome. When your property has been damaged, you’re already dealing with enough stress. The last thing you need is to battle with your insurance company over fair compensation. That’s where a public adjuster can become your greatest ally.
You should consider hiring a public adjuster when facing large or complex losses (ICRS generally represents qualifying losses of $250,000 or more after the deductible), dealing with denied or significantly underpaid claims, navigating complicated coverage issues, managing in the aftermath of a widespread catastrophe, lacking the time or expertise to handle the claim yourself, or encountering resistance from your insurance company.
Texas property owners are no strangers to devastating weather events—from powerful hurricanes in Houston to flooding in Austin, wildfires across the state, and severe storms in Dallas-Fort Worth and San Antonio. These complex claims often benefit tremendously from professional guidance through the public adjuster claim process.
Key Moments to Bring in a Public Adjuster
Timing is everything when it comes to insurance claims. Here are the critical moments when bringing in a public adjuster can make all the difference: Day One: The ideal time to contact a public adjuster is immediately after finding damage, before you even file your initial claim. This ensures proper documentation from the start and helps you avoid costly mistakes that could haunt you later. “I wish I’d called a public adjuster first thing,” shares Marcos, an Austin homeowner. “I inadvertently said some things to my insurance company that they used against me later. A public adjuster would have guided me through those initial conversations.” After a Low Offer: If you’ve received a settlement offer that seems inadequate, don’t just accept it. A public adjuster can review the offer, identify where you’re being shortchanged, and negotiate for a fair amount. Supplement Stage: Sometimes damage isn’t fully apparent until after the initial settlement. Public adjusters excel at identifying additional damage and filing supplemental claims that might otherwise go unnoticed. Post-Catastrophe Window: In the chaotic aftermath of a major disaster, securing professional representation within the first 72 hours can be crucial for proper emergency mitigation and documentation when everyone is competing for attention.Benefits vs Drawbacks Checklist
Before making your decision, it’s worth weighing the pros and cons of hiring a public adjuster: On the positive side, studies consistently show higher average settlements with professional representation. You’ll benefit from expert policy interpretation, professional documentation of damages, skilled negotiation with insurance adjusters, significant time savings, and the peace of mind that comes from knowing a dedicated advocate is handling your claim. As one Texas homeowner shared after Winter Storm Uri: “I initially thought the damage was minimal, but my public adjuster found hidden pipe damage throughout my walls that I would have never finded until it was too late. They literally saved my home.” The main drawback is the fee impact on your net recovery, subject to the written agreement and applicable state fee limits. There’s also the potential for delays if you don’t hire the right professional, and for very small claims, the service may not be cost-effective. Additionally, some adjusters may not specialize in your specific type of loss. Public adjuster fees in Texas are negotiable, and many adjusters offer sliding scales based on claim size. While their fee reduces your net recovery, the overall settlement is often substantially higher than what you might secure on your own—frequently more than covering the cost of their services. Remember what Lawrence White, an NYU Stern School of Business economics professor advises: “Try not to come across as angry. Try to come across as reasonable.” A good public adjuster helps maintain this professional approach throughout negotiations, turning potentially contentious situations into productive discussions. For more information about what makes a quality public adjuster, visit our guide on what is a good public adjuster.Public Adjuster Claim Process: Step-By-Step Guide
The public adjuster claim process isn’t just a series of steps—it’s a carefully orchestrated journey designed to maximize your recovery while keeping your stress to a minimum. At Insurance Claim Recovery Support, we’ve refined this approach through years of helping property owners across Texas get back on their feet after disaster strikes. Let’s walk through our comprehensive five-stage approach that has helped hundreds of clients steer the complex insurance landscape:Stage 1 – Intake & Authority: Launching the Public Adjuster Claim Process
Everything begins with establishing our relationship and gathering essential information about your situation. When you first reach out to us—whether by phone, email, or through our website—we review the loss and claim status to determine service fit. ICRS offers a free claim review for qualifying large losses; representation is a paid service under a written agreement. Texas claims under $250,000 may be served by the separate paid Claim Navigator advisory service. If we decide to move forward together, you’ll sign a representation agreement that clearly outlines our services and fee structure. We believe in complete transparency from day one, with no hidden costs or surprise charges down the road. We’ll then obtain a complete copy of your insurance policy, including all endorsements and declarations pages. This critical document serves as our roadmap throughout the claim process. Finally, we send a formal Letter of Representation to your insurance company, officially notifying them that we’re now handling your claim. This letter establishes our authority to communicate directly with the insurer on your behalf. “We make understanding your ‘Duties After Loss’ a priority,” explains our team. “Missing these policy-required steps can jeopardize coverage, so we guide you through each obligation to ensure full compliance.”Stage 2 – Inspection & Evidence: Core of the Public Adjuster Claim Process
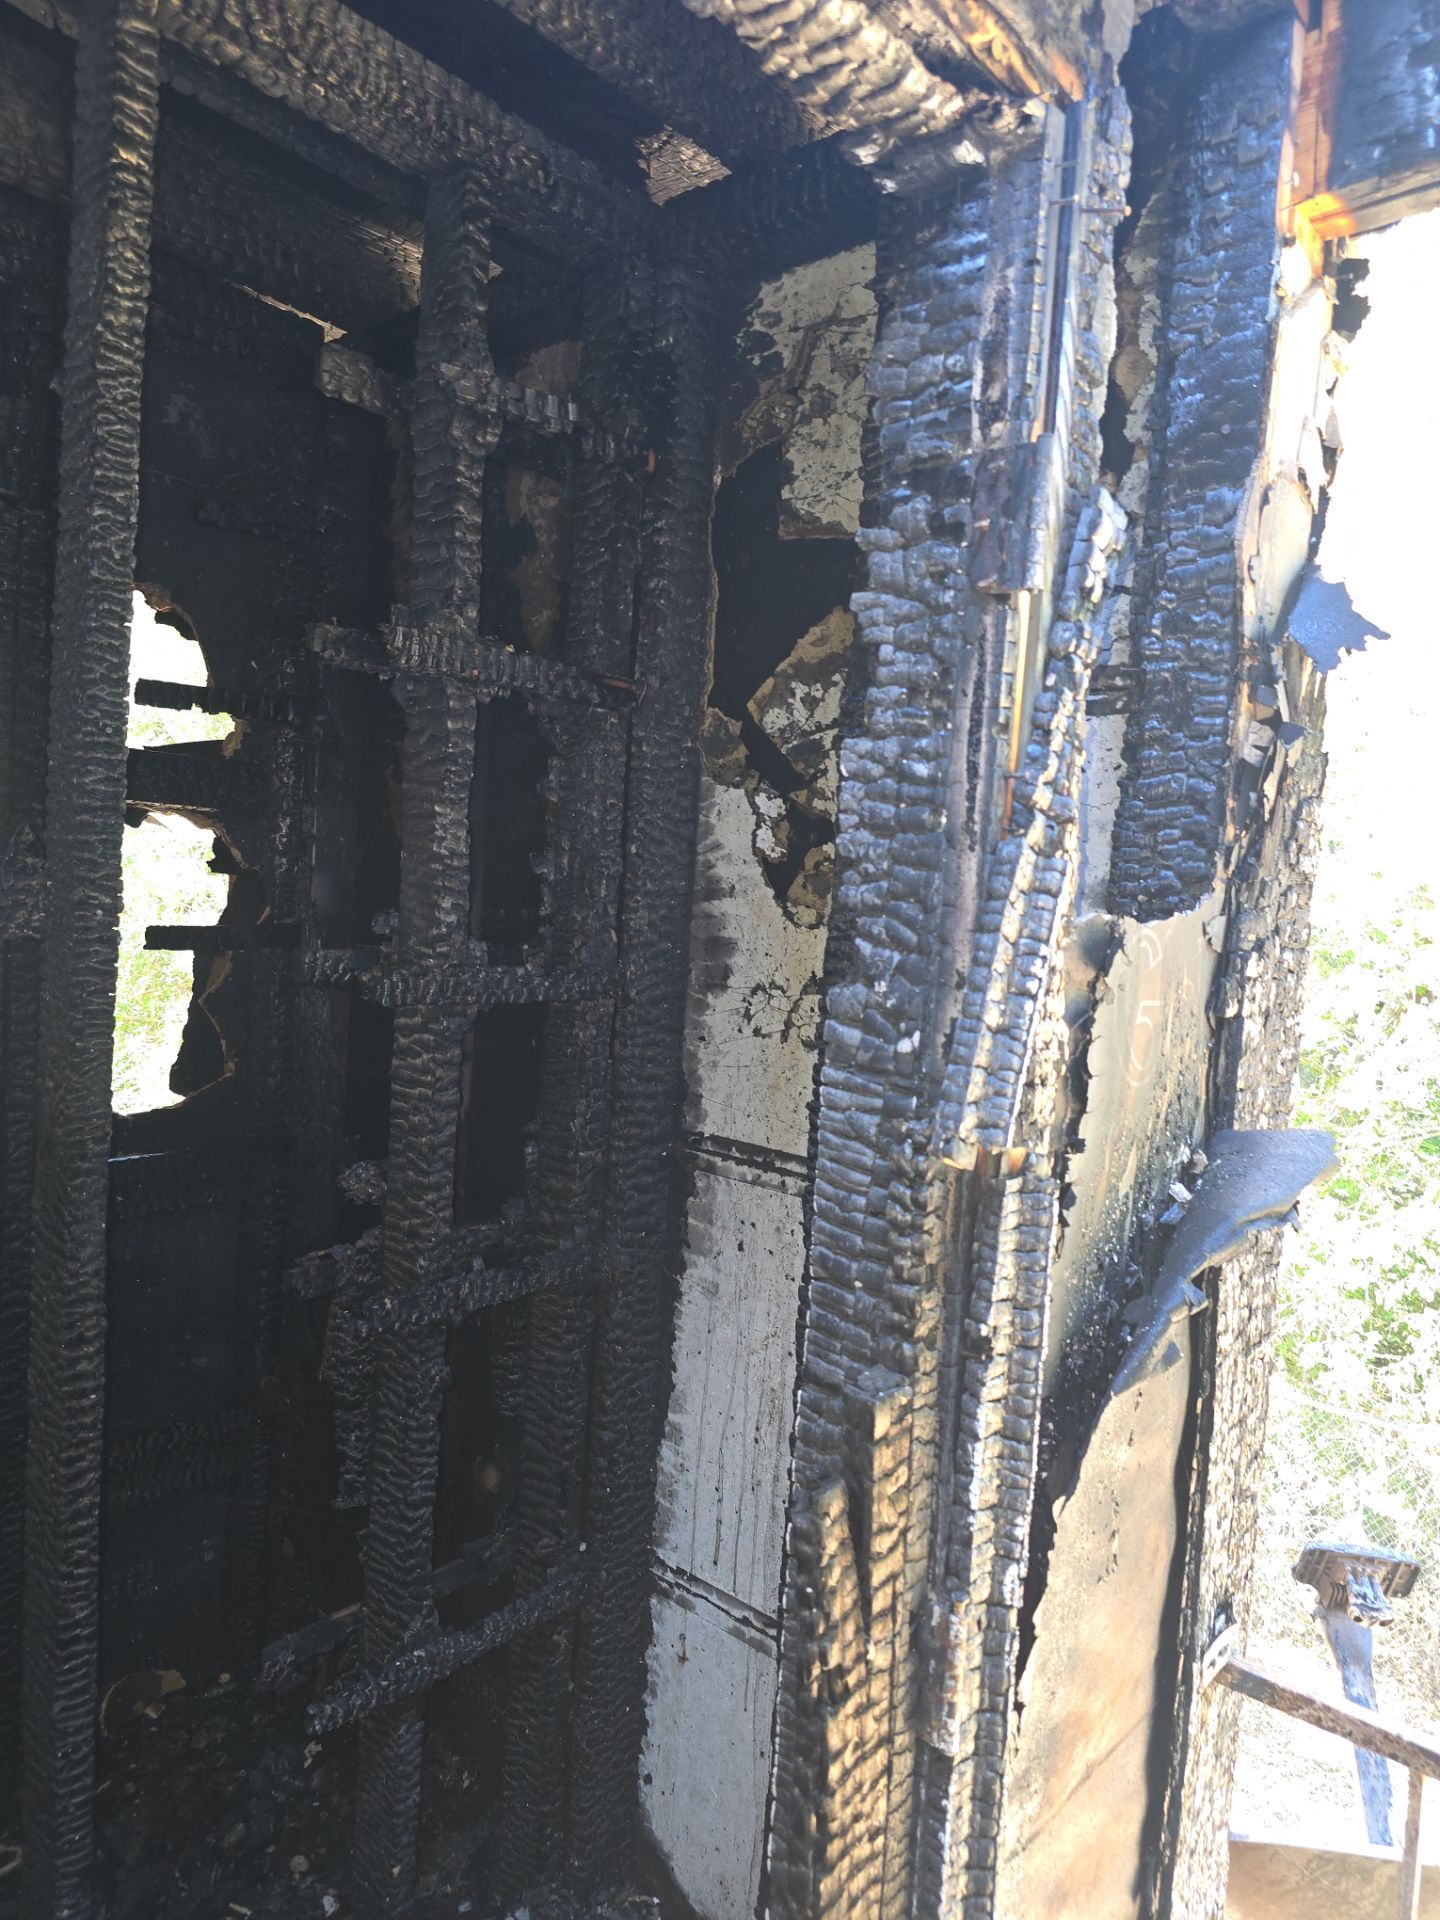
Thorough documentation forms the foundation of every successful claim. This stage is where our expertise really shines.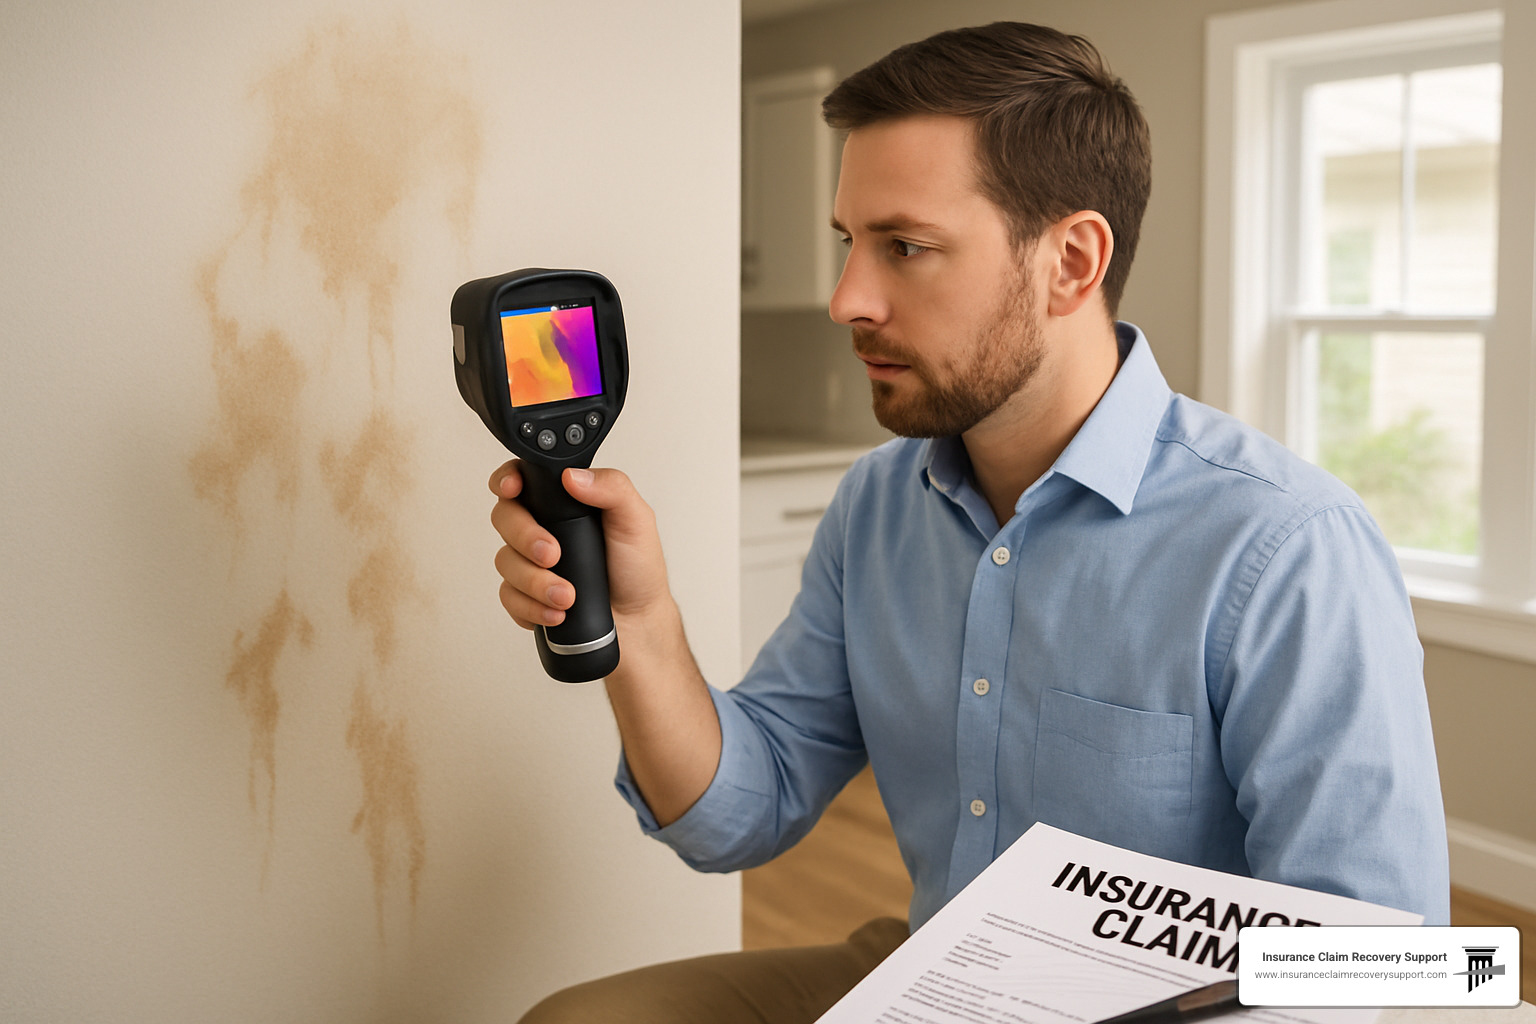 We begin with a comprehensive on-site assessment, often employing specialized equipment like thermal imaging cameras that can reveal hidden damage invisible to the naked eye. This technology has saved countless clients from finding mold or structural issues months after their claim closed.
Our team captures detailed photos and videos of all visible damage, creating a visual record that’s difficult for insurance companies to dispute. For water-related claims, we create detailed moisture maps showing the full extent of affected areas—a crucial tool for preventing future mold problems.
When your personal belongings are damaged, we help develop detailed inventories documenting each item’s condition, age, and replacement value. This meticulous approach ensures nothing falls through the cracks.
For complex situations, we bring in specialized experts—engineers, roofers, industrial hygienists—who provide professional opinions that strengthen your claim. As Don Hornstein, a University of North Carolina insurance law expert, notes: “If the house was simultaneously destroyed by flood and, concurrently by wind, it’s not covered by private insurance.” Our expertise helps identify these critical distinctions that can determine coverage.
Throughout this stage, we also oversee any emergency mitigation work to prevent secondary damage, ensuring these efforts help rather than hinder your overall claim.
Stage 3 – Valuation & Schedule of Loss
Accurately valuing your damage is perhaps the most technical aspect of the public adjuster claim process—and it’s where many policyholders leave money on the table when handling claims themselves. Using industry-standard estimating software like Xactimate (the same platform most insurance companies use), we calculate the full cost to repair or replace damaged property. This creates a level playing field when negotiating with your insurer. For personal property, we carefully determine both actual cash value and replacement cost value, accounting for depreciation where applicable. Commercial claims require additional analysis of financial records to determine business income losses and extra expenses. All these valuations come together in a comprehensive Schedule of Loss—a detailed document itemizing all damages and their associated costs. This professional presentation makes it difficult for insurance companies to minimize or overlook legitimate damages. When structural issues are involved, we incorporate engineering findings into our valuation, adding technical credibility to our assessment. We analyze building plans, pre-loss photos, maintenance records, financial statements, receipts, and contractor estimates to build the strongest possible case for your recovery.Stage 4 – Presentation & Negotiation
With thorough documentation in hand, we move to formal presentation and negotiation with your insurance company. We prepare and submit a formal Proof of Loss with supporting documentation that meets all policy requirements and deadlines. Then we present our findings directly to the insurance company’s representatives, often in face-to-face meetings with their adjusters to review damages and discuss our valuation. When insurance companies respond with desk reviews or lowball estimates—a common tactic—we challenge these assessments with technical evidence and policy language. Our negotiation strategy is built on solid documentation and deep knowledge of insurance regulations. “The printed policy forms may contradict current local adjusting practices due to evolving court rulings and regulator guidance,” notes our experience. We leverage this knowledge to counter insurance company tactics that might shortchange policyholders unfamiliar with these nuances. If direct negotiation reaches an impasse, we can pursue alternative dispute resolution mechanisms like appraisal or mediation—often resolving claims without costly litigation. For more insights on effective negotiation approaches, visit our guide on how to negotiate a settlement with an insurance claims adjuster.Stage 5 – Settlement, Payment & Close-Out
The final stage involves securing and properly handling your settlement—a process that can be surprisingly complex. We carefully review all settlement documents to ensure they’re fair, complete, and don’t contain hidden waivers that might limit your rights. Then we help steer the payment process, which often involves two-party checks requiring multiple endorsements. For property owners with mortgages, we coordinate with mortgage holders to ensure prompt endorsement of settlement checks—a frequent bottleneck that can delay your recovery. If additional damage is finded later, we handle supplemental claims to address these issues. Throughout the entire public adjuster claim process, we maintain transparent communication about progress, challenges, and expected timelines. Our goal isn’t just to maximize your settlement—it’s to provide peace of mind during a difficult time in your life. When your claim concludes, we ensure all aspects are properly closed out and documented, giving you a clear record of the resolution and protecting your rights for the future.Costs, Contracts & Compliance
For the complete explanation of fee calculations, Texas limits, supplements, and service choices, see our public adjuster fees guide.
How Do Public Adjusters Get Paid?
Public adjusters handling large property insurance losses generally charge contingency fees: a percentage of the insurance recovery, subject to the written agreement and applicable state law. For qualifying ICRS contingency representation, No Recovery, No Fee. ICRS generally represents policyholders with large losses of $250,000 or more after the deductible. ICRS generally charges 10% of the insurance recovery after the deductible for qualifying large-loss claims, subject to the written agreement and applicable state law. The deductible is subtracted before calculating this fee; the fee is a separate cost paid by the policyholder.How Much Does a Public Adjuster Cost?
Illustrative ICRS fee example| Total covered settlement | $500,000 |
|---|---|
| Policyholder deductible | $25,000 |
| Insurance company payment | $475,000 |
| ICRS fee at 10% | $47,500 |
Negotiating Fees & Understanding Caps
Here’s some good news – public adjuster fees are generally negotiable. At Insurance Claim Recovery Support, we believe in transparent pricing that’s custom to your specific situation. When discussing fees, keep these points in mind: Sliding scales are common, with many adjusters offering reduced percentages for larger claims. After all, the work required for a $500,000 claim isn’t necessarily five times that of a $100,000 claim. Prior payments matter too. If you’ve already received some money from your insurance company before bringing us on board, we may structure our fee differently for those funds. Fee exclusions might apply to certain portions of your claim. For example, some adjusters reduce or waive fees on Additional Living Expenses components. Value-added services should factor into your decision. Consider the full range of expertise and support you’re receiving when evaluating proposals. The National Association of Insurance Commissioners (NAIC) reports that unsatisfactory claim amounts and claim denials consistently rank as top consumer complaints in the insurance industry. This underscores why professional representation often proves valuable – even after accounting for the fee. According to research from the Insurance Information Institute, consumer satisfaction with claims handling varies significantly across insurance providers, highlighting the importance of expert representation.Licensing, Bonding & Standards of Conduct
Public adjusters aren’t just people who decided one day to help with insurance claims. We’re highly regulated professionals who must meet strict requirements. In Texas, public adjusters must: Maintain proper licensing by passing a rigorous exam and background check through the Texas Department of Insurance. Carry a surety bond that protects consumer interests in case of professional misconduct. Adhere to ethical standards including specific codes of conduct. For example, in Texas, we can’t solicit business between 7:00 p.m. and 8:00 a.m., can’t solicit during active disasters in certain ways, must provide written contracts with specific disclosures, and have fiduciary obligations to serve you with objectivity and loyalty. Complete continuing education to stay current with industry developments and regulations. Before hiring any public adjuster, I recommend verifying their license status using the Texas public adjuster license lookup tool. It takes just a minute and provides valuable peace of mind. The NAIC’s Public Adjuster Licensing Model Act has helped standardize these requirements across many states, though specific regulations do vary by location. This oversight helps ensure that when you hire a public adjuster, you’re working with a qualified professional who’s accountable to regulatory authorities.Choosing & Collaborating With Your Adjuster
Selecting the right public adjuster is perhaps the most crucial decision in the public adjuster claim process. The quality of your representation directly impacts your claim outcome. When evaluating potential adjusters, consider these key factors:- Experience & Specialization: Look for adjusters with specific experience handling your type of loss (fire, water, storm, etc.) and property type (commercial, residential, multifamily).
- Local Knowledge: Adjusters familiar with your area (Austin, Dallas, Houston, San Antonio, etc.) understand local building codes, weather patterns, and construction costs.
- Credentials & Licensing: Verify proper licensing and check for additional credentials like NAPIA membership or specialized certifications.
- References & Reviews: Ask for client references and check online reviews and Better Business Bureau ratings.
- Communication Style: Ensure their communication approach matches your preferences.
- Resources & Team: For large losses, confirm they have adequate staff and resources to handle your claim thoroughly.
Due-Diligence Checklist Before Signing
Before hiring a public adjuster, complete this essential due diligence:- License Verification: Confirm active licensing through the Texas Department of Insurance.
- BBB Check: Review their Better Business Bureau profile for complaints.
- NAPIA Directory: Check if they’re listed in the National Association of Public Insurance Adjusters directory.
- Interview Questions:
- How many claims like mine have you handled?
- Will you personally handle my claim or assign it to someone else?
- What is your communication process and frequency?
- How do you document and track claim progress?
- What resources do you have for my specific type of loss?
- Can you provide references from similar claims?
- Contract Review: Carefully read the contract, paying special attention to:
- Fee structure and calculation method
- Services included and excluded
- Cancellation provisions
- Timeline commitments
Working Together During the Claim
Once you’ve selected a public adjuster, establish clear expectations for collaboration:- Document Handoff: Provide all relevant policy documents, pre-loss photos, maintenance records, and correspondence.
- Communication Protocol: Establish preferred communication methods and frequency.
- Meeting Schedule: Set regular check-ins to review progress.
- Approval Checkpoints: Identify which decisions require your input and approval.
- Record Maintenance: Keep your own copies of all claim documentation.
Outcomes, Timelines & FAQs
When you partner with a public adjuster, having realistic expectations about what comes next can make all the difference in your peace of mind. Let’s talk about what you can truly expect during your claim journey.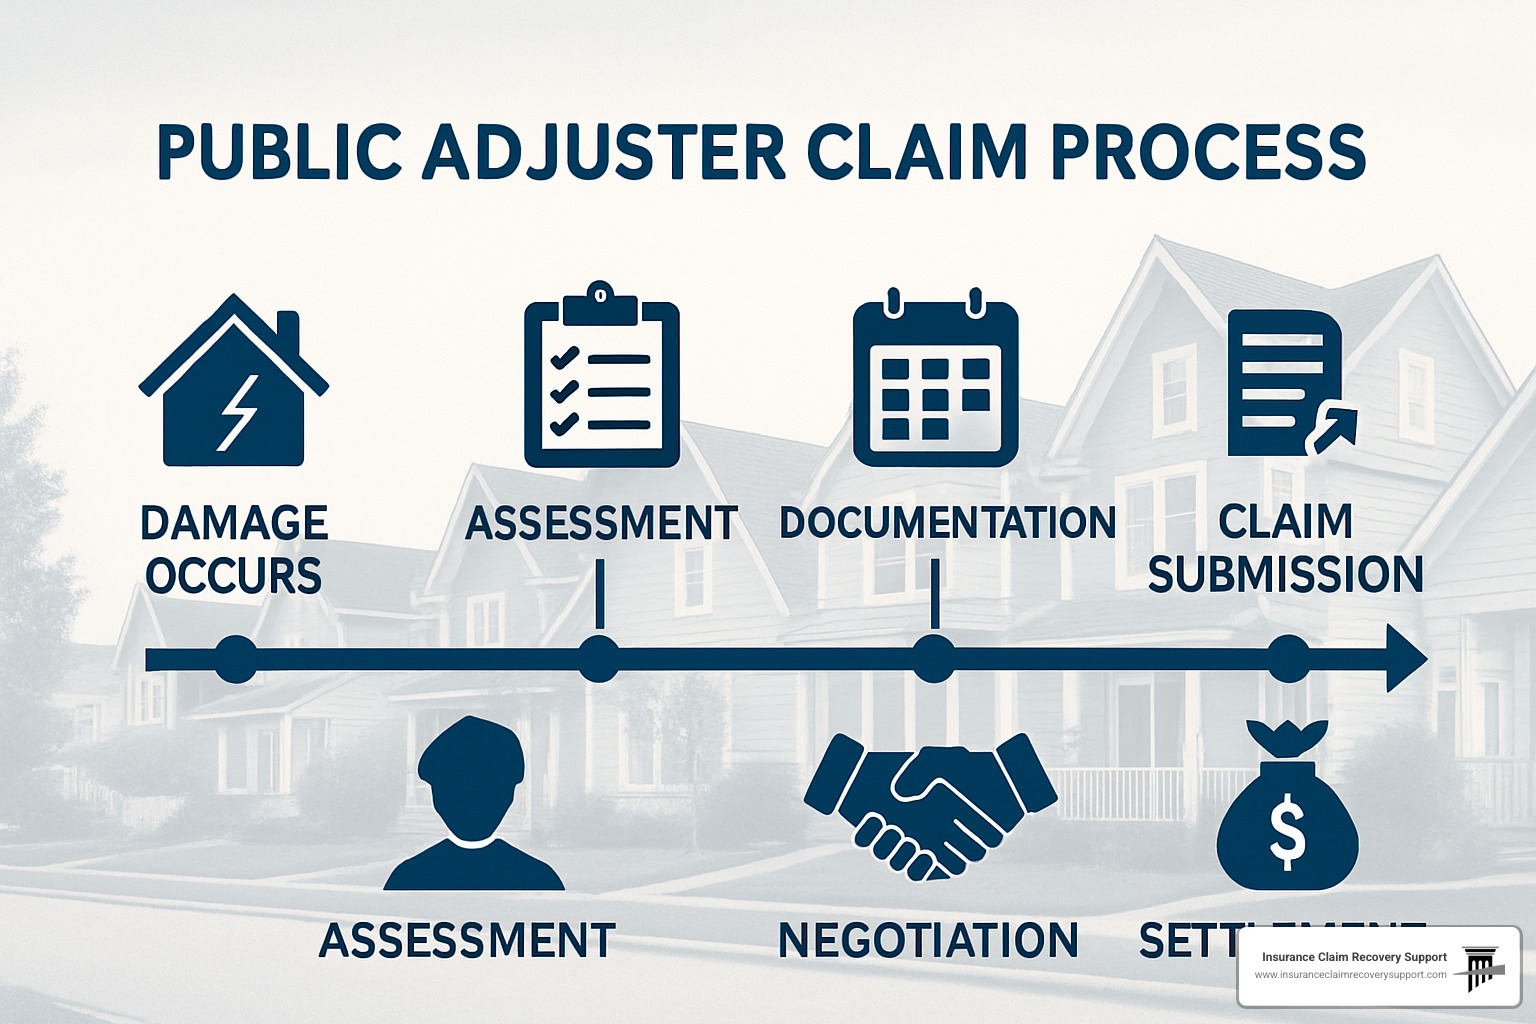 Claim outcomes depend on coverage, the scope of damage, documentation, and the circumstances of the loss. A public adjuster can help present supported losses, but no particular settlement or increase is guaranteed.
But what about timing? While every claim has its own rhythm, here’s what we typically see:
For simple claims, you’re looking at about 30-60 days from start to finish. More complex situations often take 90-180 days to resolve properly. After a major catastrophe, timelines frequently stretch longer due to the sheer volume of claims and shortage of adjusters. And if your claim becomes disputed, well, the process can extend significantly if formal resolution methods become necessary.
The good news? About 90% of insurance claims settle without ever seeing the inside of a courtroom. The not-so-good news? The quality of those settlements varies dramatically—which is exactly where the public adjuster claim process makes all the difference.