Commercial and institutional property
Identify building damage, equipment, tenant responsibilities and documented operating impacts. Churches and schools should include shared systems and temporary-use expenses in their records.
A major property loss requires more than a repair estimate. ICRS helps policyholders organize the evidence, define the documented repair scope and pursue their property insurance claim after fire, wind, hail or water damage.
Support for commercial properties, apartments, condominium associations, HOAs, churches, schools and high-value custom homes.
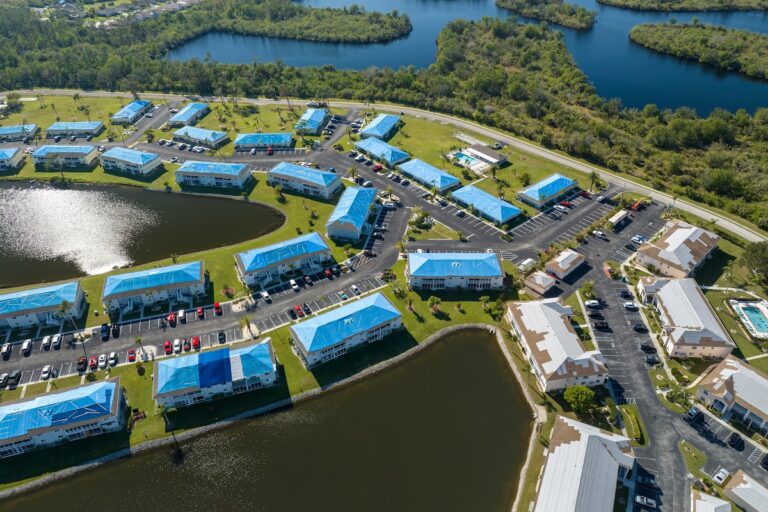
Illustrative stock photograph of storm damage; not a specific ICRS claim or Florida location.
Claims of $250,000+ after deductible: full public-adjusting representation for qualifying property losses.
Claims under $250,000: Claim Navigator provides paid strategic guidance, with the option for full representation when appropriate.
Choose a regional guide for property-specific documentation steps and claim questions. These service areas describe claim support; they do not identify separate local offices or promise inspection timing.
Identify building damage, equipment, tenant responsibilities and documented operating impacts. Churches and schools should include shared systems and temporary-use expenses in their records.
Track affected buildings, units and common property separately. Confirm the named insured, board or owner authority, and which repairs belong to the association or individual unit owners.
Document specialty materials, built-in equipment and custom finishes with photographs, specifications and suitable repair estimates. Keep emergency protection and permanent repairs separately itemized.
Describe the observed damage, event timeline and affected locations rather than assuming a cause or coverage. Wind-driven rain, rising water, plumbing losses, smoke and heat may raise different policy questions. Keep all potentially relevant policies and endorsements available for review.
For a property with prior repairs or an earlier claim, keep the old and new records separate. That distinction helps explain the current damage without treating maintenance issues or earlier work as part of a new loss.
Florida Insurance Consumer Advocate resources provide public information about insurance claims. Specific policy duties, deadlines, deductibles and coverage must be reviewed against your own documents.
Review a published ICRS apartment wind-claim example and a published apartment fire-claim example to see how claim documentation is presented. These are separate examples, not claims of a Florida result; prior outcomes do not predict another claim.
ICRS provides paid public adjusting services. Consultation and contingency representation fees depend on the service and written agreement. Coverage, representation and any recovery depend on the policy and facts of loss.
Request a property claim review
Explore paid Claim Navigator guidance for claims under $250,000
Updated October 19, 2026. ICRS exclusively represents policyholders.
FREE ICRS COMMERCIAL CLAIM RESOURCES
Seven practical PDF guides for commercial and multifamily property owners: the full Resource Kit, the First 72 Hours field guide, four companion checklists, and the 52-jurisdiction source index.
Enter your details below for immediate access to the downloads.
Educational resources only. Requesting the guides does not create a public adjuster engagement or guarantee a claim result. We handle your information under our Privacy Policy.
