Two roof estimates can look similar while describing different work. One may include fewer roof sections, different quantities, or a different repair method. Before treating the difference as a pricing dispute, compare what each document actually includes. This checklist is a way to organize questions for your contractor and insurer, not a determination that any item must be covered.
Check that the estimates describe the same property
Start with the address, inspection date, estimate version, and roof areas. Identify whether each document covers the entire roof, a specific slope, or another part of the building. If the contractor revised an estimate, retain the prior version and note what changed. Comparing an early insurer estimate with a later contractor revision without that context can obscure the issue.
Compare one work item at a time
Make a worksheet with four columns: area or item, insurer’s scope, contractor’s scope, and supporting document or question. Work through the documents in the same order. For a missing item, ask which photo, inspection finding, measurement, or explanation supports its inclusion. For a different quantity, ask what measurement method produced each number.
For example, if one estimate lists work on two roof sections and the other lists three, first identify the third section and the reason for the proposed work. Resolve that scope question before comparing total prices. This example illustrates a document-review method; it does not establish that replacement of any roof section is owed.
Separate proposed repairs from insurance payment
A contractor’s price and an insurer’s payment explanation answer different questions. Ask the insurer to explain how the policy terms and figures shown in its documents relate to the proposed payment. Identify references to the deductible, depreciation, limits, or other adjustments, and keep those questions separate from the contractor’s repair scope. Do not assume an estimate total is the amount of the check you will receive.
Connect the estimate to the damage record
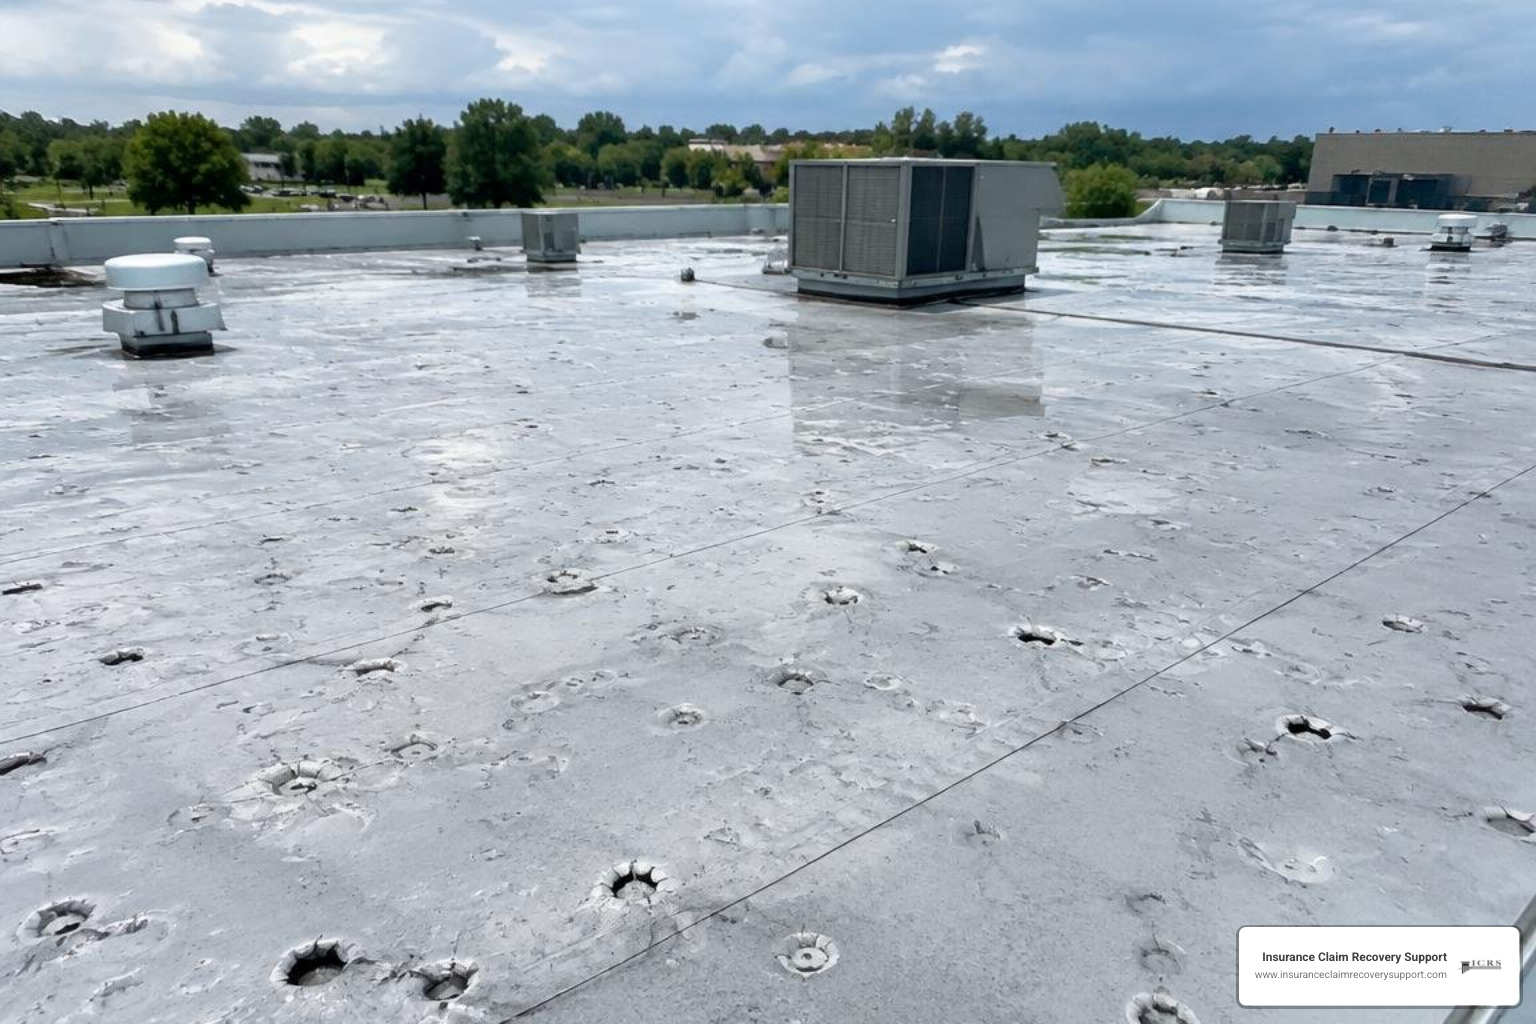
Use dated photos, inspection findings, and the reported loss information to connect a disputed item to an observed condition. A weather report and a repair estimate serve different purposes. The existence of a storm does not establish the cause of every roof condition. Arrange any necessary roof inspection with a qualified professional; do not climb onto a damaged roof to collect material for a consultation.
Send a focused question with supporting records
The Texas Department of Insurance’s guidance on payment disagreements recommends explaining why you disagree and supplying supporting documentation, such as a contractor’s estimate. An organized list of specific differences is easier to address than a message that only states that one total is higher. Keep copies of what you submit and the response.
Get a second look at the documents
Claim Navigator is a separate $250, 45-minute online advisory consultation for property damage claims under $250,000 after the deductible. The session includes discussion of your materials and prioritized next steps, plus a recording and transcript. It does not include insurer negotiation, claim representation, a separate written strategy report, or ongoing support. Full-service representation requires a separate agreement.
The Claim Navigator hail claim consultation is designed to help you discuss the documents you already have and prioritize questions. It is not an on-site roof inspection and does not guarantee that an insurer will accept a different estimate.