A denial letter can leave a property owner unsure whether the disagreement concerns the cause of damage, a policy term, missing information, or the amount of the loss. Start by organizing the written record. The goal is to understand the insurer’s stated position and identify the question you need answered, rather than assume every denial has the same explanation.
Read the letter alongside the claim documents
Keep the complete letter, including attachments and the date it was sent. Highlight the reasons the insurer gives and any policy wording it identifies. Separate the insurer’s description of the facts from its references to coverage. Create two headings in your notes: “What the company says happened” and “Which policy provisions it cites.”
If the explanation is unclear, identify the passage you want the company to explain. The Texas Department of Insurance explains reasons a claim may be denied or closed without payment. Those are different outcomes, so confirm which description applies to your claim.
Build a record of the condition and the response
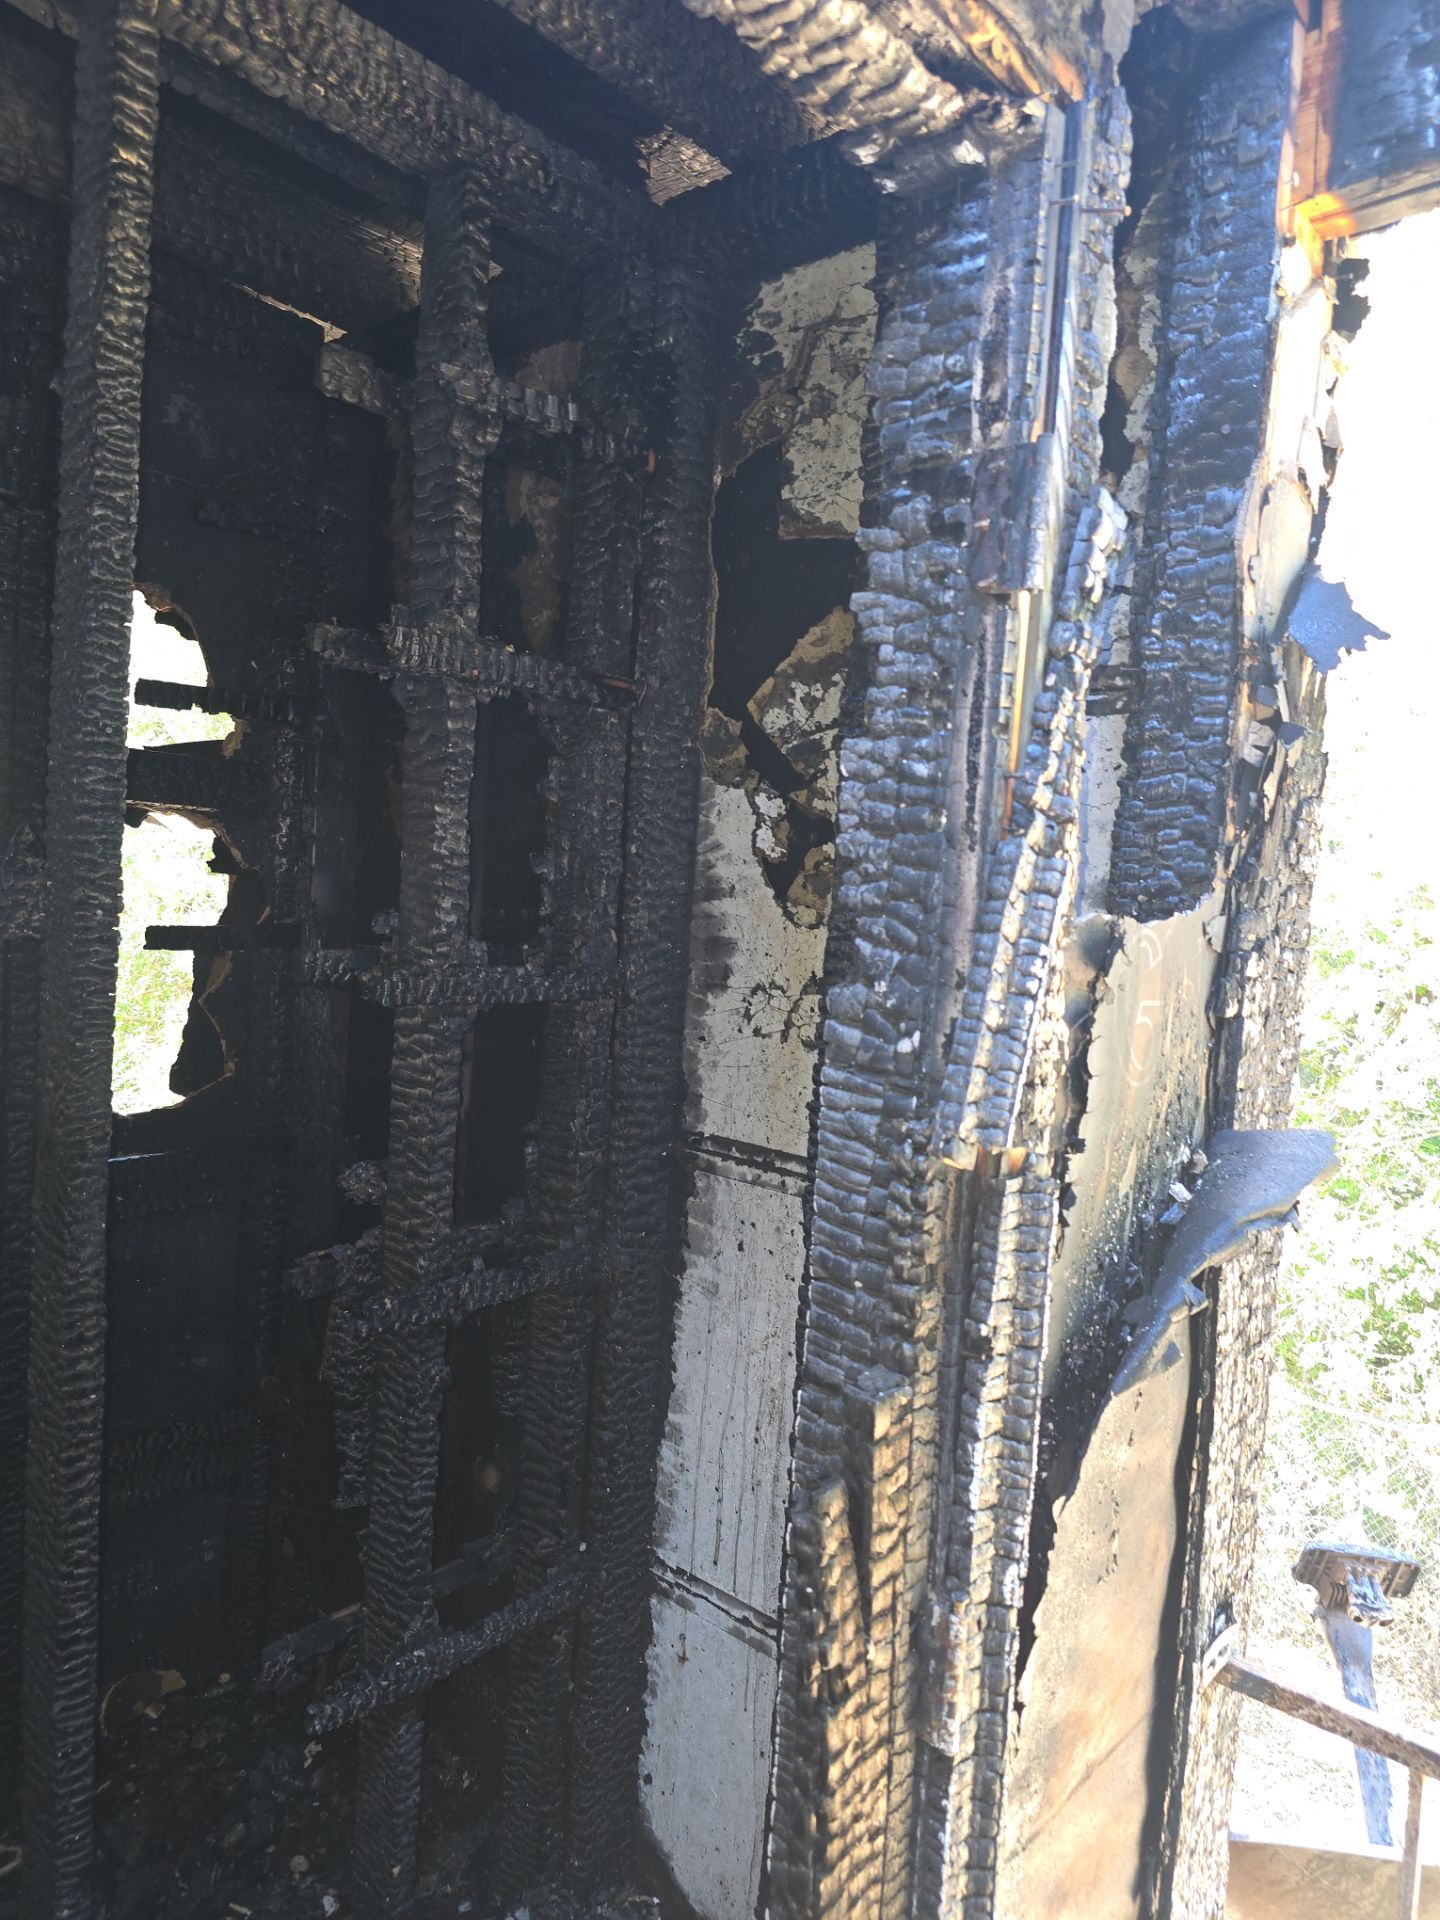
Place the declarations page, policy, endorsements, insurer correspondence, inspection findings, and estimates in separate folders. Add photos with dates and location labels where available. Keep temporary-repair and mitigation invoices with a note explaining which area of the property they concern. Avoid editing original photos; use labeled copies when organizing the discussion.
Match each question to a document
Write one question per row in a simple question log. Next to it, list the insurer’s explanation, the document you think is relevant, and what remains unclear. For example: “The letter describes long-term damage; which inspection observations support that description?” This is a request for an explanation, not a conclusion about the cause of loss.
If you have a contractor’s estimate or inspection report, identify the specific observation you want discussed. A different opinion can help frame a question, but the report’s existence alone does not establish policy coverage or require a particular payment. Keep a copy of every item you provide to the company.
Keep a communication timeline
Record when you reported the claim, when inspections occurred, when you received letters, and what additional information was requested. Preserve emails and notes from calls. Mark any dates or requested actions mentioned in your actual policy and correspondence. Do not rely on a general online article to decide which deadline applies to your situation.
Choose the next conversation deliberately
You may need clarification from the insurer, more documentation from a contractor, advisory guidance, representation, or legal advice. Those services have different roles. If you have questions about legal rights or deadlines, speak with a qualified attorney. For a focused discussion of your claim materials and next-step questions, review the consultation scope before booking.
Claim Navigator is a separate $250, 45-minute online advisory consultation for property damage claims under $250,000 after the deductible. The session includes discussion of your materials and prioritized next steps, plus a recording and transcript. It does not include insurer negotiation, claim representation, a separate written strategy report, or ongoing support. Full-service representation requires a separate agreement.
See Texas property claim advisory consultation details. Claim Navigator does not represent you in disputing a denial through this consultation and does not promise to reverse an insurer’s decision.